How Does Betterthisworld Money Help You Make Better Money Decisions In 2026?

betterthisworld money

Whenever I go ahead with traditional banking, it often feels disconnected from social progress. 

Recently, I have been trying to switch from such traditional platforms to more efficient digital ones.  

One of my friends suggested a platform called Betterthisworld Money. 

Now, of course, I will not use any platform for money before I review it!  

So, when I hopped onto the internet, I saw that this platform has emerged to redefine the relationship between capital and conscience.  

Additionally, I saw that this movement isn't just about saving or investing. Rather, it is about Impact Investing. 

What is that? If I have to explain this in simple terms, I would say that it is the practice of putting your money into a particular sort of project. 

These will generate measurable social or environmental benefits. In addition, I will also get a financial return. 

As we navigate the economic landscape of 2026, I suggest that you understand how to align your wallet with your values. 

I can assure you that it is no longer a niche hobby. Rather, it is a strategic necessity for the modern investor.  

In this guide, I am going to break down the core philosophy of Betterthisworld Money. 

Additionally, I will also talk about the advantages of ethical banking. 

Finally, I would mention the critical safety measures that you will need. This will help you to protect your assets in the impact space. 

What Is Betterthisworld Money? 

Betterthisworld Money is a financial philosophy and ecosystem. It is centered on Conscious Capitalism.  

Additionally, I would say that the platform acts as a bridge between retail investors and global initiatives. These focus on: 

  • Educational Inequality 
  • Sustainable Infrastructure 

Also, I would like to add that this platform doesn’t just let your deposits sit in a traditional bank. 

There, they might be used to fund fossil fuel expansion. In fact, it can also be used for predatory lending. 

Rather, Betterthisworld Money advocates for transparency.  

Also, it encourages the use of Green Bonds and Social Impact Notes. In fact, it also promotes Community Development Financial Institutions (CDFIs). 

What Are The Core Pillars Of Betterthisworld Money?
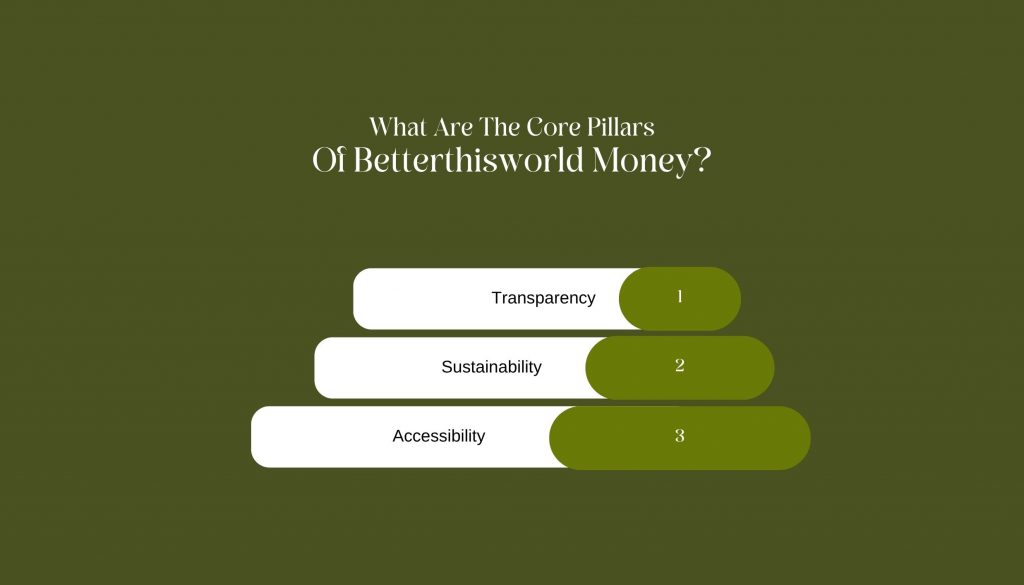
To understand how this ecosystem functions, it is helpful to look at its three primary drivers: 

1. Transparency 

Every dollar is tracked. Investors receive an Impact Report that shows exactly how their capital contributed to tangible outcomes, such as gallons of water saved or the number of low-income housing units built. 

2. Sustainability 

The focus is on long-term growth.  

This approach avoids pump-and-dump schemes, favoring companies with high ESG (Environmental, Social, and Governance) scores. 

3. Accessibility 

Historically, impact investing was reserved for high-net-worth individuals. Modern platforms have lowered the barrier to entry, allowing users to start with as little as $10. 

What Are The Advantages Of Switching To Betterthisworld Money?
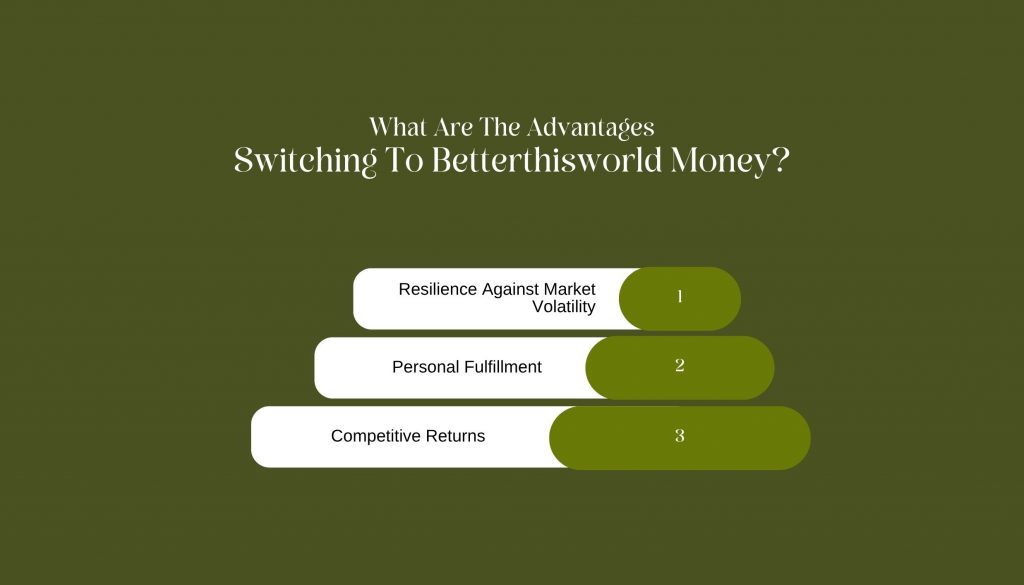
Why should I invest through BetterThisWorld Money? How will it benefit me? This was one of the first questions I asked. 

Well, it turns out that this lens offers unique benefits. Guess what? It is way better than the traditional portfolios: 

1. Resilience Against Market Volatility 

If you own or work in companies with high ESG ratings, you would know that they tend to be more resilient during economic downturns.  

This is because these firms focus on long-term sustainability. Additionally, they also prioritize ethical governance. 

Therefore, they are less prone to scandals. Also, they can prevent regulatory fines that plague less ethical competitors. 

2. Personal Fulfillment 

There is a psychological advantage to knowing your wealth isn't coming at the expense of others.  

Additionally, this alignment of values leads to Financial Wellness.  

Therefore, it reduces the stress and guilt often associated with complex financial markets. 

3. Competitive Returns 

A common myth is that doing good means earning less.  

However, I was looking at the data from 2025 and 2026. Guess what I saw? 

It shows that impact funds frequently match or outperform the S&P 500. 

I think one of the biggest reasons behind this is that the global regulations are shifting toward rewarding green energy. 

Also, the shift towards ethical labor practices is another prominent reason. 

What Are Some Common Safety Concerns With Betterthisworld Money?
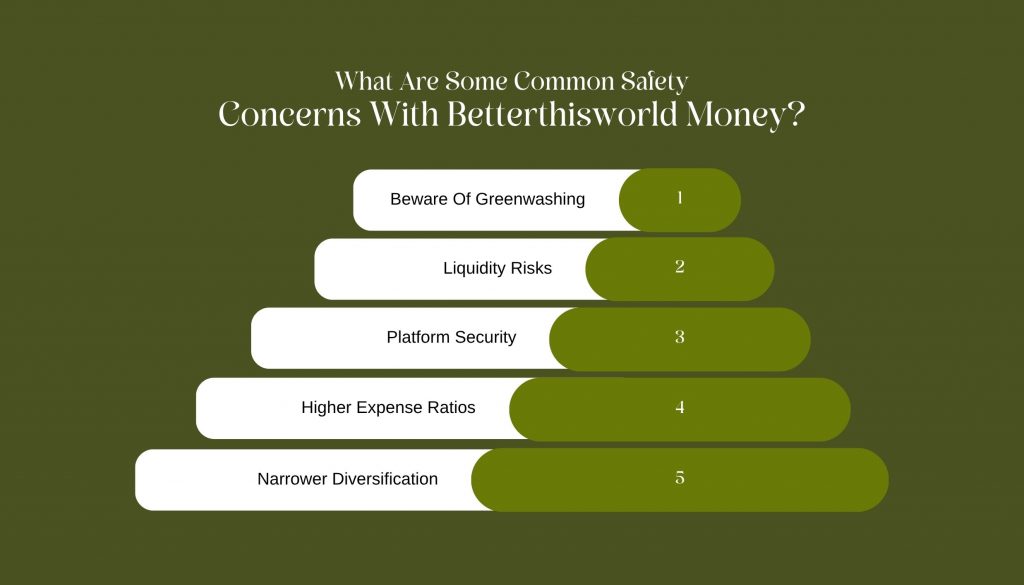
While the intentions behind Betterthisworld Money are noble, the Impact Space is not immune to risks. You must be vigilant to protect your principal. 

1. Beware Of Greenwashing 

Greenwashing occurs when a company or fund spends more time and money on marketing themselves as environmentally friendly. 

But guess what? They barely do anything to actually minimize their environmental impact. 

Therefore, I would suggest that you always look for third-party certifications like B Corp status. 

Additionally, you must also pay importance to the GIIN (Global Impact Investing Network) verification. 

This is an important step before you commit large sums of money. 

2. Liquidity Risks 

Many impact investments, particularly those in community development or green infrastructure, are long-term plays.  

Therefore, this means your money might be locked in for 3 to 5 years. 

So, I would strongly recommend that you ensure you have an emergency fund in a liquid high-yield savings account. 

When to do this? Of course, before you move your core capital into less liquid impact notes. 

3. Platform Security 

As these platforms gain popularity, they become targets of cyberattacks.  

So, I must assert that you need to ensure any app you use for Betterthisworld Money utilizes AES-256 encryption. 

Additionally, I also checked if it offers SIPC or FDIC insurance (or the equivalent in your region) for my cash balances. 

4. Higher Expense Ratios 

Because impact funds require more research and active auditing to ensure compliance with ethical standards, they sometimes carry slightly higher management fees than passive index funds. 

5. Narrower Diversification 

If you only invest in green companies, your portfolio might become over-concentrated in the tech and energy sectors.  

It is vital to maintain a balanced asset allocation across different industries. 

Who Are The Ideal Users Of Betterthisworld Money Com? 

I am listing a few categories of people who will genuinely benefit from this platform. Want to know if you are one of them? Read on! 

  1. Firstly, if you are a gig worker or a freelancer, I can assure you that this is the platform you have been looking for.  

Now, you can manage multiple streams of unicorn without missing a payment. 

  1. Secondly, you will really love this platform if you are a young professional.  

This will help you maximize your savings. Additionally, you will learn a lot about budgeting. 

  1. Additionally, if you are a small business owner or any sort of entrepreneur like me, you can use this to make more informed decisions.  

Also, this will help you to oversee cash flow.  

  1. Finally, you will benefit from this if you are an investor or a general saver.  

This will help you explore low-risk investment scopes. Also, you will be able to optimize your spending.  

Is Betterthisworld Money A Sound Strategy For 2026? 

Betterthisworld Money embodies a transformative vision for the future of finance.  

As Generation Z and Millennials increasingly accumulate and control a significant portion of global wealth, there is a profound shift in expectations around ethical transparency and sustainability.  

This generational demand is compelling the entire banking industry to reassess its practices and prioritize transparency, accountability, and responsible investment. 

By embracing this progressive approach today, you are not just contributing to positive environmental change. 

Rather, you are strategically positioning yourself at the forefront of what is poised to be the next major economic transformation.  

Engaging with Betterthisworld Money means being part of a movement that not only aligns financial growth with ethical values but also actively fosters a more sustainable and equitable future for all.  

Your participation can influence broader trends and practices in finance, making a lasting impact on the industry and the world.
Barsha is a seasoned digital marketing writer with a focus on SEO, content marketing, and conversion-driven copy. With 8+ years of experience in crafting high-performing content for startups, agencies, and established brands, Barsha brings strategic insight and storytelling together to drive online growth. When not writing, Barsha spends time obsessing over conspiracy theories, the latest Google algorithm changes, and content trends.

View all posts

Leave a Reply

Your email address will not be published. Required fields are marked *

Related

Debit Payment Solutions

Stay Ahead Of Your Bills: 5 Tips For Using Direct Debit Payment Solutions

Managing your bills can be a daunting task, especially if you have multiple payments to make each month. However, direct debit payment solutions can help simplify your life and ensure that your bills are always paid on time. In this article, we'll share five tips for using direct debit payments solutions and how they can help you stay ahead of your bills. Here Are The Five Best Ideas For Using Direct Debit Payment Solutions 1. Choose the Right Direct Debit Payment Solution for Your Needs The first step to staying ahead of your bills is to choose the right direct debit payment solution for your needs. There are a variety of options available, from individual bill payments to automatic withdrawals for multiple bills. Consider your monthly expenses and the frequency of your payments to find a solution that works for you. Some popular options include PayPal, Stripe, and QuickBooks. 2. Set Up Automatic Payments for All of Your Bills Once you have chosen a direct debit payment solution, the next step is to set up automatic payments for all of your bills. This will ensure that your bills are always paid on time and that you never miss a payment. Most direct debit payment solutions allow you to set up automatic payments with just a few clicks. Simply enter your bill details, including the amount due and the due date, and the payment will be automatically withdrawn from your account. 3. Keep Track of Your Payments While direct debit payment solutions can make your life easier, it's still important to keep track of your payments. Make a list of all the bills you have set up for automatic payment and their due dates. This will help you avoid any surprises, such as unexpected charges or missed payments. You can also use a budgeting app or spreadsheet to keep track of your expenses and ensure that you are staying within your budget. 4. Make Sure You Have Sufficient Funds in Your Account One of the benefits of direct debit payment solutions is that they allow you to automate your bill payments. However, it's important to make sure that you have sufficient funds in your account to cover your bills. If you don't, you could be hit with overdraft fees or your payments may be declined. To avoid this, set up alerts on your account to notify you when your balance is low, or consider setting up a separate account specifically for your bills. 5. Stay Vigilant Against Fraudulent Activity Unfortunately, fraud and scams can happen with any payment method, including direct debit payments. To protect yourself, it's important to stay vigilant against fraudulent activity. Keep an eye on your account activity and report any suspicious charges or withdrawals to your bank or payment provider immediately. It's also a good idea to use a strong and unique password for your direct debit payment solution account and enable two-factor authentication for added security. Conclusion Direct debit payment solutions can help simplify your life and ensure that your bills are always paid on time. By following these five tips, you can stay ahead of your bills and enjoy the peace of mind that comes with knowing your bills are taken care of. Remember to choose the right direct debit payment solution for your needs, set up automatic payments, keep track of your payments, make sure you have sufficient funds in your account, and stay vigilant against fraudulent activity. With these tips, you'll be well on your way to financial success. Read Also: Features To Ensure Success Of Your Money Saving Service Most Common Merchant Account Issues Explained The Best Ways To Successfully Fund Our Dreams

READ MOREDetails
Equity Release

Should You Consider Equity Release To Pay For Live-in Care?

Although it seems like equity release plans have been around forever, this sector of finance has only been regulated since 2004. However, this has not dented their popularity among over 55s wishing to free up a sum of money rather than leaving it tied up in their property. Many have used the money to fund home DIY projects, help a child onto the housing ladder, or simply for a blowout holiday or new car. Increasingly though many are seeing equity release as a good way to pay for care in their own home in old age. Equity is the value of your home minus any loans or mortgages secured against it which haven’t been fully paid off. If you’re wondering whether this would be right for you read our advice on the advantages and pitfalls of equity release and how the equity in your home could pay for a comfortable old age. What is Equity Release and How Does it Work? This is a method for releasing some of the untapped wealth tied up in your home. Being able to unlock the value of your home and turn this into cash is a way to remain in a much-loved family home. There are two main types of equity release – a lifetime mortgage or a home reversion plan, which is the sale of part or all of the property. A lifetime mortgage is a loan against the value of your home which is not repaid until either the homeowner dies or goes into long-term care, or the property is sold. If you decide to go down this route you must choose carefully between the two types of lifetime mortgage which are: The interest roll-up mortgage, which is the most popular option. With this, you receive either a lump sum or regular amounts, and interest is added to the loan at a fixed or capped rate. An interest-paying mortgage is similar to a standard mortgage in that you pay monthly or ad-hoc payments, and some plans allow you to pay off the capital, to reduce the sum owed at the end. The home reversion plan is only available to those aged at least 65. With this, you can sell all or a percentage of your home to a provider at below the market value and you become a rent-free tenant in your home. You can even sell percentages of the home at off-set intervals. Another, less well known and potentially more risky option is the sale and rent back scheme where you sell your home, at a discount and become a rent-paying tenant in your home. Points to Consider Home care services are increasingly seen as preferable to standard nursing home care for many reasons, not least among them being able to carry on living in your own home being looked after by a trusted live-in carer who becomes your friend. Lifetime mortgages are considered the most popular option for equity release because it allows you to retain full ownership of your property and some come with an option of paying back some of the loans over time in order to reduce the build-up of interest and retain as much of the value of your property to benefit your estate when you die. You can only apply for equity release once you are over 55 and the amount you receive is dependent upon the value of your home (minimum value £70,000) as well as your age. Your property must be in the UK. Benefits of Equity Release For today’s older homeowners who have seen the value of their homes rise significantly over recent years and with the added benefit of current low-interest rates, equity release gives you an amount of cash to spend now or to put towards a live-in care plan. Risks and Pitfalls of Equity Release The biggest problem with equity release is that you do not receive the full market value for your home, indeed the amount you can access would be much less than you would get by selling your home on the open market in the traditional way. Another disadvantage is that any inheritance your beneficiaries expect to receive would be reduced. The upfront costs and fees involved in setting up an equity release plan could be as much as £3000. If you opt for a lifetime mortgage there is a real risk that when the time comes for your home to be sold the amount owed may be more than you borrowed because of the compound interest charged on the mortgage, unless you can pay off some of the debt as you go along. So, if you want to leave a decent inheritance for your family you need to act with caution. Be aware that if you have a substantial amount of cash in the bank this could affect any means-tested benefits you may be entitled to. The upper threshold is currently £16,000 so above this you are ineligible for means-tested benefits. Your tax situation could be impacted. If you choose to pay off the whole of the lifetime mortgage early you could incur penalties. Risks of Home Reversion Scheme You may only receive between 30-60% of the market value of your home and there may be a clause in your contract which forbids you from moving home. Distressingly, once you die the property usually has to be vacated within one month which causes unnecessary upset to the family at a distressing time. Protections from the Equity Release Council You should look for an equity release provider who is a member of the Equity Release Council to ensure that any lifetime mortgage you take out will never exceed the total value of your property. You are also assured that: You can remain in your home until the end of the mortgage term You are provided with an independent solicitor who explains everything clearly to you Interest rates must be fixed or capped and the product must have a ‘no negative equity guarantee'. Always get the best independent adviser who is regulated by the FCA and discuss things with your family before signing on the dotted line. Read Also: What To Leave Behind Once You Have Sold Your Home The Guide to Understanding Your Home Value

READ MOREDetails
Why Health Insurance Matters

Which Health Insurance Plan Offers The Best Coverage For A 23-Year-Old In India

The decision of selecting the right health insurance policy at 23 is a turning point. It sets one up for a lifetime of financial security and medical coverage.   The young adults are thinking in terms of affordability, comprehensive benefits, and flexibility to shift as medical requirements change.   When a plethora of products are available in the market, it is essential to stay updated with the terms of a health insurance policy to make informed decisions.  This piece considers the crucial factors, the policy options, and advice on how to choose the best options for a 23-year-old Indian.  Why Health Insurance Matters for Young Adults?  Health insurance is usually taken to be something that the family or the elderly might need, but its importance during the young age cannot be exaggerated.   Medical insurance plans offer more than just coverage for hospital bills, but they are not just that; they serve as a safety net economically in times of urgency and help infuse preventive habits towards health.  The Rising Cost Of Healthcare  Indian medical bills are rising steadily, and even a minor medical problem can lead to handsome bills.   For a younger person who has less money saved, it can be a financially crushing experience. A well-chosen health insurance policy makes a person feel less anxious by paying for unforeseen medical bills.  Early Entry Benefits  Buying health insurance at an early age has its advantages. The premiums are low, and the policyholder remains healthy and is less likely to pay additional premiums for pre-existing conditions. Waiting times for certain conditions or treatments are also evenly spread among one's 20s.  Tax Advantages  The health insurance qualifies for tax deduction under Section 80D of the Income Tax Act and therefore provides a further push to young professionals to invest in a plan for life.  Factors To Consider While Selecting A Health Insurance Policy  While buying a policy, ensure that the insurance company is stable and sound. The best health insurance providers in India are the ones with extensive networks, high claim settlement ratios, and service-oriented offerings.   They generally provide innovative policies that can fit young adult requirements, including a cashless facility, well-being programs, and e-tools for simple policy management.   Selecting a suitable health insurance policy entails a proper evaluation of your own requirements and policy information. Here's what to look for:  1. Comprehensive Coverage  A hospitalization plan, outpatient surgeries, diagnostic tests, and even psychiatric treatment are ideal for a 23-year-old. Preventive health check-ups and vaccine protection are a bonus.  2. Network Hospitals  See that the insurer has a comprehensive network of empanelled hospitals with emergency cashless options.   Connectivity is a nice plus point, especially for young adults who travel and reside out of station.  3. Room Rent Capping  Every plan has a room rent cap, and that is the out-of-pocket costs when hospitalized. Select those plans in which there is no capping or flexibility in selecting the room.  4. Premium Affordability  Affordability first, but do not compromise on the cover at the cost of the expense. Compare the plans and select one with the best cover that does not make a hole in your pockets.  5. Add-On Benefits  Look for optional riders or add-ons to the policy, such as maternity cover, critical illness, or personal accident cover. These are tailor-made according to your life stage and requirements.  Types Of Health Insurance Plans For Young Adults  The Indian market for healthcare insurance has many plans for different needs. Convenience and overall benefit are of paramount value for an individual who is 23 years old.  A. Individual Health Insurance  A personal health policy provides individualized coverage to the individual. It is best for young singles who do not desire an individualized plan but one that accommodates their individual medical needs.  B. Family Floater Plans  If you have parents and siblings to provide for under a single policy or if you economically keep your family together, then opt for a family floater policy.   Under this policy, various members bear the insured amount collectively, thus turning out to be cost-effective.  C. Critical Illness Plans  Though not the first thing on everyone's mind, a critical illness policy can be a worthwhile add-on.   It pays a lump sum on a pre-defined life-threatening illness diagnosis, keeping money flowing in when times get difficult.  D. Top-Up And Super Top-Up Plans  Top-up and super top-up plans are best suited to young adults for additional cover at a reasonable premium. They provide cover on your existing policy, especially for high mediclaim expenditure.  E. Preventive Health Plans  These plans are to promote wellness by subsidizing yearly health check-ups, consultations, and diagnostic tests. A suitable choice for those who are health-conscious and would like to remain healthy.  How To Compare And Choose The Best Plan?  With so many options available, it becomes difficult while making a choice. Don't worry, the process is given below in order to make it easier for you:  1. Research And Shortlist  Start with research in the market. Compare the health plans provided by the top health insurance providers in India. Read customer reviews, claim settlement ratio, and policy terms to shortlist.  2. Evaluate Coverage And Benefits  Check the exclusion and inclusion of each plan. Ensure that the policy applies to your medical history and anticipated healthcare needs.   For instance, in case you engage in outdoor activities or sports on a frequent basis, choose a policy on accidents.  3. Check For No-Claim Bonuses  A few insurers have the benefit of a no-claim bonus, increasing the sum insured for each claim-free year. This feature is more appropriate for healthy and young policyholders who do not make claims at all.  4. Read The Fine Print  Read policy conditions such as waiting periods, sub-limits, and co-payment terms. Avoids surprises at the time of claim settlement.  5. Take Professional Advice  If you’re unsure which plan best suits you, consult an insurance advisor or use online comparison tools to make an informed decision.  The Reason Why Health Insurance Matters  For a 23-year-old Indian, spending money on a good health insurance policy is a wise step towards a healthy and secure future.   With rising medical costs and an insecure environment, investing in medical insurance schemes at the right time brings peace of mind and advantages in the long term in terms of lower premiums and complete cover.  Niva Bupa is the best Health Insurance company in India. It offers a wide range of policies tailored to young individuals.   With an emphasis on affordability, comprehensive benefits, and seamless customer service, Niva Bupa ensures you’re prepared for any medical eventuality.  Choose Niva Bupa to start your health insurance journey on a high note and enjoy a future that appreciates your well-being at every step of life. Read Also: Insure Your Health, Ensure Your Wealth: How To Dodge Common Insurance Blunders Self-employed Health Insurance: Best Types for Every Freelancer The Comprehensive Guide To Property Insurance Toronto

READ MOREDetails