



Amazing Ways to Maximize Your Profit at Trading (As a Beginner on Edge!)
Published on: 20 November 2020
Last Updated on: 12 September 2024
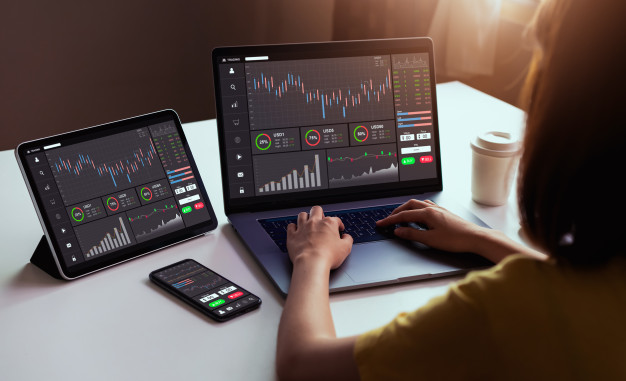
The traders invest money in making good profits in business. People hope for good returns to become rich in the Forex market.
But maximizing the probability of profits cannot be done within a short time. The investors apply different types of techniques for increasing the chance of making money.
By developing sound knowledge about the field, a person will be able to get good returns from the market. There are several types of techniques for maximizing profits. These are being discussed here.

Popular

Technologies For Creating A Startup Idea
20 Feb 2023

How to Download Facebook Videos on Android?
07 Feb 2019

7 Rules of Effective Ecommerce Web Design
28 Jan 2021

Why Are Online Transactions Convenient?
07 Dec 2023

Recent
Related
Michigan Auto Insurance : Everything You Should Know About
Living and driving in Michigan will mean that you need to have Michigan auto insurance because the state requires all drivers to have adequate coverage if they are going to be on the road. Auto insurance will provide you and your family with financial and liability protection necessary in the event of any accidents or if you are a victim of theft. The cost of insurance in Michigan has been rising the past few years just as the population has. As of 2019, Michigan has a little over 9.987 million people living in the state with a lot of the people in Detroit, Motown, Grand Rapids, Warren, Sterling Heights, Lansing, Ann Arbor, and Flint. The Tort System: When you are looking at Michigan auto insurance quotes you may run across information about the tort system which is used in a few states. This means that when an accident occurs someone must be held liable, or guilty for its occurrence. This person and their low-cost auto insurance Michigan are responsible for covering the damage and medical costs for both sides. The person who is guilty will then have the added repercussion of increased premiums. Minimum Amounts: Auto Insurance Michigan comes with a few different options. First, you will want to understand what kind of coverage you must have at a minimum, especially if you are considering a no down payment car insurance. The minimum requirement for Michigan state auto insurance is 50/100/25-this means 50,000 for any injuries to a person and 100,000 when more than one person is involved and coverage as the minimum limit for damage of 25,000 as the most basic requirements. You should also check out sr22 insurance michigan if you're a high risk motorist. Because of these requirements, you should make sure to ask plenty of questions when getting auto insurance quotes in Michigan. Getting Cheap Auto Insurance in Michigan: Don't go with a no-name auto insurance company located in the middle of nowhere in Michigan. Go with trusted licensed MI insurance companies whom you can feel comfortable and secure that they will be able to go to should you get into any accidents. Shop around among different Michigan auto insurance companies to get the cheapest rate possible. More competition between the different auto insurance companies in MI means better savings for you, the consumer. Remember to compare the entire policy and not just the price. Some car insurance companies may offer low rates but may not cover any more than what is required by law. Another way to get cheap car insurance with no down payment in Michigan is to maintain a good driving history with no speeding tickets or accidents. Other Ways to Lower Car Insurance Costs- 1. Auto Insurance Discounts: Take advantage of special discounts available to those who insure their home and automobile with the same Michigan insurance company. Other Common Ways to Get Discounts: Be a good student Get Car Safety Equipment Like Air Bags Install anti-theft devices 2. Increase your Deductible: Increase your deductible to the highest amount you can afford. The keyword is affording. The deductible is the amount you need to pay out of your own pocket before the auto insurance company starts to pay for anything. The higher amount your insurance deductible is, the lower your rate will be. Do not increase your deductible to $1,000 from $500 if you do not feel comfortable paying $1,000 out of pocket. 3. Insuring Home and Auto: By insuring your vehicle and home with the same company, consumers can save as much as 20% on their total premiums between the two policies. Insure MI's free online form allows you to apply for a quote for the home and auto insurance combo to see how much your insurance policy will cost. Insurance Fraud in Michigan: There was a recent report that Michigan is the number one state in the US for cheap Michigan auto insurance that is a fraud. In fact, in 100,000 residents there were more than 150 cases of fraud. What this means for you is that when you are searching for cheap auto insurance with no down payment you really need to keep your focus on the traditional providers. If you end up driving under fraudulent insurance you can wind up with a ticket, your car impounded, and heavy fines. Michigan does have a coalition working to eliminate this criminal offense. They work together with the different law enforcement departments to break up different rings. One raid, in particular, helped save more than 15 million dollars, which also helped to reduce their rates by close to 25%. While getting the best auto insurance in Michigan may seem like you should hunt for the least expensive of the possible insurance quotes. Because of the minimum requirements and the high rate of fraud you should certainly consider taking your time, reading through the literature your company provides, and definitely going with a well-known company. Compare Free Michigan Auto Insurance Quotes Online: There are many insurance agents in Michigan who can provide you with top-notch quality customer service. Get cheap auto insurance rates in Michigan by comparing free online quotes from MI auto insurance companies in our network including reputable providers like Youngamericainsurance.net, Good2go Auto Insurance, or Rodneydyoung.net. Take advantage of many insurance websites’ free comparison service that allows you to fill out one form and receive offers from multiple competing insurance agents serving everywhere in Michigan such as Livonia, Dearborn, and Battle Creek. Apply for a free no-obligation quote online and talked to insurance agents to see which policies may be best for your situation. Read Also: 5 Tips For Transport & Logistics Business Owners Before Investing In Insurance Appliance Repair Process Getting Your Appliances Back In Top Shape Navigating The Long Haul: Maintaining Your RV’s Black Tank
READ MOREDetails
The Impact Of Automation On Payroll And Compliance
In the rapidly evolving business environment, automation has emerged as a transformative force, reshaping various operational aspects, including payroll and compliance processes. This technological advancement has significantly impacted how businesses manage their financial obligations and adhere to regulatory standards, much like workforce management systems have revolutionized employee scheduling and task allocation. Automation in payroll and compliance offers many benefits, ranging from enhanced accuracy to improved efficiency. This article dives into the impact of automation on these critical business functions, shedding light on its benefits and the future it heralds for organizations. Streamlining Payroll Processing The advent of automation in payroll processing has revolutionized the way businesses approach this critical function. Beyond merely automating calculations, sophisticated software solutions offer integrated time tracking, direct deposit setups, and even mobile access for on-the-go management. This ensures that every aspect of payroll—from initial hours worked to final payment—is handled precisely and efficiently. Automated systems adeptly manage varying tax rates and legal requirements for businesses operating across different states or countries, ensuring compliance and accuracy regardless of geographic complexities. The result is a streamlined process that saves time and significantly reduces the administrative burden on staff, allowing businesses to allocate resources to areas that drive growth and innovation. Enhancing Accuracy And Reducing Errors Automated payroll systems have become invaluable in enhancing the accuracy of financial transactions and reducing errors. By removing manual data entry, the risk of human error significantly decreases, leading to more reliable payroll outcomes. These systems are designed to automatically update in response to changes in tax laws, employee benefits, and other variables, ensuring that every payment is calculated based on the most current information. Furthermore, they offer detailed records and reports that can be quickly reviewed and audited, providing additional oversight. This meticulous approach to payroll not only safeguards against compliance issues but also builds trust among employees, who can be confident in the accuracy and reliability of their paychecks. Improving Compliance With Regulatory Changes The dynamic nature of tax laws and employment regulations makes compliance a moving target for many businesses. Automated payroll systems are equipped to handle these changes seamlessly by incorporating updates directly into their calculations and reporting features. This automation ensures that businesses remain compliant without needing to monitor and adjust to new regulations manually. It also provides a significant advantage in risk management, as the system can alert businesses to potential compliance issues before they become problematic. By leveraging automation, companies can navigate the complex regulatory compliance landscape more quickly and confidently, minimizing exposure to penalties and legal issues. Enhancing Employee Self-Service Capabilities Implementing employee self-service capabilities through automation has transformed the employee experience regarding payroll and benefits management. These platforms empower employees to take charge of their personal information, view detailed pay histories, and access year-end tax documents independently. This level of transparency and control is a convenience for employees and fosters a sense of empowerment and engagement. Additionally, by decentralizing these tasks, HR departments are relieved of routine inquiries, allowing them to concentrate on strategic initiatives that contribute to the company's culture and growth. This shift improves operational efficiency and enhances the overall workplace environment by promoting a culture of transparency and self-sufficiency. Facilitating Data-Driven Decision Making In payroll and compliance, automation provides more than just operational efficiencies; it offers strategic insights. The data collected and analyzed by automated systems can inform various business decisions, from budgeting and financial planning to workforce development strategies. This wealth of data enables companies to identify trends, such as overtime usage or departmental labor costs, allowing for more informed decision-making. By knowing the financial implications of these trends, businesses can optimize their operations, forecast future costs more accurately, and strategically plan for growth. This level of analysis was previously unattainable with manual processes, highlighting how automation not only streamlines administrative tasks but also provides a strategic advantage. Prioritising Cybersecurity In Automated Systems An additional point to consider in the context of automation in payroll and compliance is the critical importance of prioritizing cybersecurity. As businesses rely increasingly on digital platforms to manage sensitive employee information and financial data, the potential for cyber threats grows. Implementing robust security measures, including encryption, multi-factor authentication, and regular security audits, is essential to protect this data from breaches. Furthermore, educating employees about cybersecurity best practices can help mitigate risks associated with phishing scams and other digital threats. By prioritizing cybersecurity within automated payroll and compliance systems, businesses can safeguard their data, protect their employees' information, and maintain the integrity of their financial operations in the digital age. Conclusion In conclusion, the impact of automation on payroll and compliance is profound, offering businesses the opportunity to streamline processes, enhance accuracy, improve regulatory compliance, empower employees, and make informed decisions. As technology advances, automation will likely play an increasingly central role in these areas, much like workforce management systems have become integral to managing modern workplaces. The benefits of automation in payroll and compliance are clear, promising a future where businesses can operate more efficiently, accurately, and compliantly, ultimately contributing to their overall success and sustainability. Read Also: Common IT Security Risks in the Workplace Everything You Need To Know About PKI In Cybersecurity Would Your E-commerce Website Pass the Cybersecurity Test? Here are 3 Things You Could be Doing Wrong
READ MOREDetails
Institutional Accounting Fraud, Third-Party Escrow Vacuums, And The Structural Collapse Of Wirecard AG
On 25 June 2020, Wirecard AG, the shining jewel of Germany's fintech landscape, valued at €24 billion at its peak, filed for corporate insolvency. Founded as a payment processor, the company rapidly rose to inclusion in Germany's elite DAX 30 stock index. It positioned itself as a global challenger to legacy digital transaction networks. However, the enterprise’s underlying operational framework was structurally compromised by a massive, multi-year balance sheet manufacturing operation. This case study analyzes how a strategic asset-inflation trap and unverified third-party processing loops systematically distorted the company's financial health. The structural breakdown occurred over a chaotic two-week window when auditors demanded proof of €1.9 billion in cash balances supposedly held in Asian escrow accounts. When the trust banks confirmed those funds did not exist, the ghost balance sheet collapsed instantly. This operational disaster led to immediate criminal indictments for its core executive leadership team, triggered a complete overhaul of German financial regulatory laws, and remains a definitive case study in corporate oversight failure. Problem Statement: The Tech Alchemy Of Third-Party Acquiring (Tpa) Loops The collapse of Wirecard was not a standard case of business stagnation or a drop in market volume. Instead, it was an intentional, systemic corporate fraud built around a network of phantom transactions and unaudited offshore escrow accounts. The fraud's core mechanism relied on Third-Party Acquirers (TPAs). In high-risk sectors or global territories where Wirecard lacked local operating licenses, it paid outside payment processors to handle client credit card transactions. Wirecard then logged its share of these high-margin transactions as massive corporate revenue. To mislead investors and regulators, Wirecard claimed that the cash generated by these international third-party processors was routed into highly secure trust escrow accounts managed by local banks in the Philippines and Singapore. However, investigative audits revealed that these high-volume merchant portfolios were almost entirely fabricated. The company used a network of fake digital entities and fabricated transaction sheets to inflate its reported processing volumes. So, this relied on self-printed documentation to trick external auditors while concealing its burning core operating losses. Granular Timeline Of The Strategic Meltdown The operational collapse scaled with unprecedented velocity, stripping a major European fintech giant of its entire market cap in less than a week: Strategic Phase TimelineFinancial EventUnderlying Systemic ImpactJan 2019 – Oct 2019The Financial Times publishes investigative exposes detailing faked asset records and manufactured revenues across Asian operations.Wirecard management flatly denies the claims and files criminal complaints against journalists.March 2020KPMG conducts a highly anticipated independent forensic audit and states it cannot verify the authenticity of major TPA revenue lines.Public shareholder trust drops, and short-selling restrictions fail to stabilize the asset value.18 June 2020EY auditors announce they cannot trace €1.9 billion in missing cash balances supposedly stored in Philippines banks.The stock drops 60% in a single day as the company's financial records are exposed as fraudulent.22 June 2020Wirecard's executive management officially admits that the missing €1.9 billion "likely does not exist."CEO Markus Braun is arrested, and COO Jan Marsalek flees the country to avoid arrest.25 June 2020Wirecard files official corporate insolvency filings with the Munich court.The company becomes the first active component in DAX 30 history to go bankrupt. Structural Vulnerability Matrix: Root Causes Of The Failure An institutional post-mortem of Wirecard AG highlights three distinct, compounding risk management flaws that left the enterprise completely defenseless against a forensic check: · Complete Regulatory Capture Germany’s financial regulator, BaFin, suffered from severe systemic blindness. Also, it didn’t waste time investigating Wirecard's suspicious books. Rather, BaFin launched criminal market-manipulation investigations against the journalists. It also did the same to short-sellers who exposed the fraud, effectively shielding the corrupt executives. · Passive Confirmation Auditing For over a decade, external auditing teams accepted simple, third-party balance screenshots. Additionally, it kept unverified email letters from local Asian trustees as absolute proof of the €1.9 billion cash holdings. However, they failed to contact the primary banks directly to verify the ledger positions. Also, they allowed a basic paper trail to survive multiple audit runs. · Severe Governance Deficits The corporate board operated without any baseline transparency. Chief Operating Officer Jan Marsalek held absolute control over the platform's international shadow transactions, managing complex shell companies and moving massive corporate assets without any internal accounting oversight or secondary board approvals. Post-Crisis Regulatory Remediations The fallout from the Wirecard scandal shattered the reputation of European financial markets and forced international authorities to implement sweeping structural reforms: · Complete Regulatory Overhaul The German government passed the FISG Act (Financial Market Integrity Strengthening Act). This sweeping legislation completely restructured BaFin, granting the agency direct powers to audit major corporate accounts independently, while introducing a strict 10-year rotation cap for external auditing firms. · The Auditing Sector Shockwave The multi-year failure to catch the phantom assets permanently damaged the credibility of top global auditing houses, triggering massive legal liability suits from institutional investors and driving structural changes across corporate vetting networks worldwide. · Venture Capital Vetting Realignment Modern tech investors shifted away from tracking simple top-line processing volumes. Due-diligence protocols now demand independent, automated tracking of underlying payment streams, matching reported numbers against hard transaction files to eliminate faked books. Comprehensive Lessons for Corporate Treasury and Capital Allocation Analyzing the structural failure of Wirecard highlights several essential risk management rules for modern corporate treasuries and venture capital investors: · Verify Your Financial Positions Directly Never trust a third-party image, an unverified PDF screenshot, or an isolated email letter from a regional middleman bank as proof of your cash holdings. Ensure your internal treasury teams run independent, automated bank integrations to track your cash reserves on a 1:1 basis. · Implement Strict External Vendor Audits If your company relies heavily on Third-Party Acquirers or independent outsourcing networks to generate revenue, enforce continuous compliance checks. Track actual, granular transaction logs to verify that your business growth is driven by real consumer demand rather than faked digital logs. · Eliminate Single-Executive Management Silos Establish tight internal controls that prevent a single executive or operations officer from managing international shell networks or bank routing pipelines without oversight. Furthermore, you must ensure all cross-border cash transfers require multi-signature approvals from independent board members. This is an important step to prevent unaudited cash vacuums. The Dynamics Of The Wirecard Scandal Explained The failure of Silicon Valley Bank was a classic asset-liability mismatch. But Wirecard's collapse was a case of institutional accounting fraud and broken regulatory oversight. Moreover, Wirecard did not fail because the digital payment market slowed down. Rather, the Wirecard scandal happened because its leadership manufactured billions in fake processing revenue to hide a failing business core. Therefore, to understand it better, it is important that you study this structural breakdown. Then, modern financial officers can learn to look past flashy tech valuations and prioritize direct transaction checks. Also, you will be able to manage corporate capital with absolute, data-driven certainty.
READ MOREDetails