2 Reasons to Invest in GoldBullion Even If You’ve Never Invested in an Asset Before 

Published on: 15 December 2021 Last Updated on: 31 October 2024
gold bullion

Why should you consider investing in gold bullion even if you’ve never invested in an asset before?

Gold bullion is a potentially valuable investment option for beginning investors looking to build a financial portfolio that can minimize risk and maximize potential returns.

Gold has a better portfolio weight than many other asset classes, and it’s also more affordable than other assets. (Silver bullion is even more affordable.)You don’t need to be rich to invest in gold bullion, nor do you have to invest in a lot of gold bullion for your investment to pay off in the short and long term.

Here are two reasons beginning investors may want to invest in gold bullion.

What Is A Gold Bullion?
What Is A Gold Bullion?

First off, though, let’s define gold bullion.

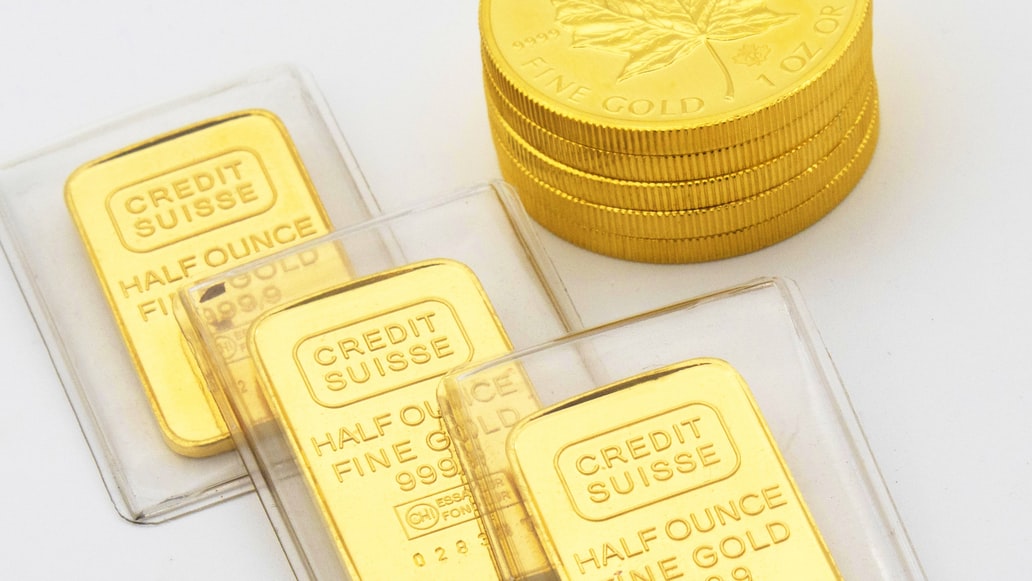
Gold bullion refers to gold bars, ingots, and coins officially recognized as being made of at least 99.5% pure gold. Gold bullion is kept as reserves at banks, governments, and institutional investors.

The standard size of gold bullion bars and coins is 1oz.

In North America, you can use bullion coins as legal tender.

In Canada, sales tax doesn’t apply to gold bullion, and gold bullion can be included in RRSPs and other tax-deferred income plans. Some Canadian companies permit Canadians to include gold bullion in their retirement portfolios.

How To Buy and Selling Gold Bullion?

There are many reasons to consider buying and later selling gold in Toronto and elsewhere. Two reasons are that gold bullion is considered:

  1.       A safe-haven asset
  2.       A hedge against inflation

2 Reasons Are Making The Gold Bullion A Perfect Investment
2 Reasons Are Making The Gold Bullion A Perfect Investment

You will hear millions of names and types of investments in the money market. But every investment has some risk factors. Unlike the other money investment types, Gold Bullion has multiple facilities, which makes this a safe asset.

Here are the two reasons. Take a look at these and know the advantages of the gold bullion investment.

1st Reason to Invest in Gold Bullion: Gold is Considered a Safe-Haven Asset

Gold bullion is a safe-haven-type asset. This is a specific type of asset that tends to increase or retain value over time.

That gold is considered a safe-haven asset doesn’t mean investing in it is risk-free. No investment is risk-free.

But gold tends to perform exceptionally well during times of economic uncertainty, like the earlier days of the COVID-19 pandemic and the 2007-2008 global financial crisis.

In fact, during the earlier days of the COVID-19 pandemic, the price per ounce of gold surpassed USD 2,000 for the first time in history.

Recently, the price of gold per ounce has been hovering around USD 1,800.

2nd Reason to Invest in Gold Bullion: Gold is Considered a Hedge Against Inflation

An asset that hedges against inflation is an asset that can keep pace with or even surpass inflation.

Investing in inflation hedges like gold bullion is a smart way to save money. During periods of inflation, gold tends to appreciate.

If you were to put your money into a traditional savings account, your money would likely fall behind the rate of inflation over time. Consequently, the value of your money in the future would turn out to be less than the value of your money now.

However, if you were to put your money in gold bullion, over time, your money might keep pace with or even surpass inflation, so that the value of your money in the future might turn out to be worth as much or even more than the value of your money now.

The Bottom Line

There are many reasons why beginning investors could benefit from investing in and buying and selling gold bullion.

In addition to being a relatively affordable safe-haven asset and hedge against inflation, gold is considered a strategic asset.

Also, gold bullion is easy to purchase. All you need to do is head over to your local gold bullion dealers (although to be sure, it’s always a good idea to try out a few options before settling on the one that will give you the best deal).

Later, when you’re ready to sell your gold bullion, you can take it to a gold bullion dealer that buys gold bullion. Your goal when doing so is to sell your gold bullion as close to the spot price as possible.

Read Also:
Content Rally wrapped around an online publication where you can publish your own intellectuals. It is a publishing platform designed to make great stories by content creators. This is your era, your place to be online. So come forward share your views, thoughts and ideas via Content Rally.

View all posts

Leave a Reply

Your email address will not be published. Required fields are marked *

Related

Tax Implications

Tax Implications For Independent Event Planners

As an independent event planner, you have the freedom to set your own schedule and take on exciting projects that you’re passionate about. However, being your own boss also comes with certain responsibilities, including managing your taxes. Freelancers often face challenges in maximizing their tax savings and properly filing their taxes due to their unique work situation. In this article, we’ll explore the tax implications of being an independent event planner and provide helpful information to ensure that you’re on top of your tax obligations. 1099 Income and Taxes As an independent event planner, you may receive 1099 income, which refers to income received from a client or business that is not your employer. When you receive 1099 income, you’ll need to pay both the employer and employee portion of Social Security and Medicare taxes. This is known as self-employment tax. The self-employment tax rate is currently 15.3%, but only applies to the first $132,900 of your net earnings. Once you reach this threshold, the rate drops to 2.9%. It’s worth noting that the self-employment tax rate applies in addition to your regular income tax rate. This means that you’ll need to factor in both taxes when calculating your overall tax liability and use a quarterly tax calculator. To make things a bit easier, you can use a 1040 ES calculator to estimate how much you’ll need to pay in taxes for the year and to determine how much money you should set aside throughout the year to cover your tax bill. The 1040 ES calculator takes into account your 1099 income, self-employment tax, and any other income you may have throughout the year. Claiming Deductions and Maximizing Tax Savings One of the benefits of being self-employed is the ability to claim deductions that can help reduce your taxable income and lower your overall tax bill. However, freelancers often struggle with identifying which deductions they're eligible for and how to properly claim them on their tax returns. As independent event planners, you may be eligible to deduct expenses such as office supplies, equipment, software and subscriptions, travel expenses, and marketing expenses. However, it's crucial to save records of what you spend in order to claim them properly, and in case you get an IRS audit. You can also consider setting up a retirement account, such as a Solo 401(k) or a SEP IRA, which can help reduce your taxable income while ensuring that you're saving for your future. Managing these different accounts and write-offs is often a lot of work for one person. Most people find that their financial situation gets more complex as their business grows. Professional owner tax consulting helps you stay organized throughout the year. This type of support makes it easier to spot savings you might miss on your own. It also helps you prepare for changes in tax laws that affect small companies. Having a clear plan in place keeps your focus on your clients instead of paperwork. Tax Implications of Incorporating Your Business Many independent event planners operate as sole proprietors, which means that they’re an individual who owns and operates a business. However, there are benefits to incorporating your business, such as limited liability protection and potential tax savings. Additionally, corporations are eligible for more tax deductions than sole proprietors, including health and life insurance premiums, employee benefits, and certain business travel expenses. Making your business incorporated can also help reduce your total tax liability. For example, if you’re earning a high income as a sole proprietor, you may be subject to the top income tax rate of 37%. However, if you incorporate your business and structure it as an S-corporation, you can pay yourself a salary and receive the rest of your income through distributions, which are taxed at a lower rate. 2023 Self-Employment Tax Calculator Looking ahead to future tax years, it’s always a good idea to stay informed about changes to tax laws and regulations. The self-employment tax rate may change from year to year, and it’s important to stay on top of these changes in order to accurately estimate your overall tax liability. The self-employment tax calculator 2023 can help you estimate how much you’ll owe in self-employment taxes for the year, based on the latest tax rates and regulations. By using this calculator, you can ensure that you’re setting aside enough money throughout the year to cover your tax bill and avoid any unpleasant surprises come tax time. Conclusion As an independent event planner, managing your taxes can be a bit daunting. However, by staying informed about your tax obligations, identifying available deductions, and incorporating your business if necessary, you can minimize your tax liability and maximize your tax savings. Utilizing tools such as the 1040 ES calculator and the self-employment tax calculator 2023 can also help streamline the tax planning process and ensure that you’re in compliance with the latest tax regulations. Read Also: 6 Ways to Stay Sales Tax Compliant Know the Applicable Stamp Duty when Gifting an Asset Commonly Misunderstood Facts About The Employee Retention Tax Credit

READ MOREDetails
Trading

Amazing Ways to Maximize Your Profit at Trading (As a Beginner on Edge!)

The traders invest money in making good profits in business. People hope for good returns to become rich in the Forex market.   But maximizing the probability of profits cannot be done within a short time. The investors apply different types of techniques for increasing the chance of making money.   By developing sound knowledge about the field, a person will be able to get good returns from the market. There are several types of techniques for maximizing profits. These are being discussed here.  Check the Broker The traders must select the right broker to continue the transaction process. A trading platform is very important for the buying-selling process, and the broker provides this platform.   So, when a person chooses a platform, he or she needs to make sure that the trading platform works better and suits him or her properly.   The broker charges a fee for their services. The business should choose a broker who prefers a fixed spread. This will help the investor to reduce the costs. You should focus on the facilities provided by the broker.  Follow the Plan Properly  When an investor can control the risk, they will get good rewards. For this, people must execute the roadmap properly so they can stay on the right track to accomplish the goal.   A person must generate a proper plan and should be back testing this so that they can identify the plan's workability.   Considering the different phases of the Forex market, traders need to develop a plan and change some necessary things to adjust to the situation.   People should develop a sense of discipline that will help them apply the strategies accurately. However, those who are involved in bond trading must choose a high-end broker like Saxo. Usually, bond traders trade with a big sum of money. So, investing a big sum of money with an unregulated broker is a very risky approach.  Limit the Currency Pairs Sometimes, people try to trade the different currency pairs to see which provides more profit.   But trading several types of pairs can force the investors to switch from one price pattern to another price pattern.   Therefore, the businessmen can miss the condemning period of the business field. So, to avoid the losses, a person tries to limit the pairs as one pair influences another pair.  Limit the Leverage Investors should take leverage based on their account balance. Taking excessive leverage can create a problem for them. This can wipe out their account balance and can destroy the traders’ trading careers.   Many brokers offer moderate leverage, which helps maintain a balance between cost and assets. People take excessive leverage to make more trade and more profits. But the person needs to take the leverage that can control the risk and help to get good rewards.  Maintain the Risk-Reward Ratio  The risk-to-reward ratio refers to the proportion between the stop-loss order and the take-profit order.   To get good results, a person should use these orders accurately. If people cannot spend lots of time in front of the screen, they can secure their current position by setting the stop-loss.   An investor should identify how much loss he or she can tackle in place of making good profits. Some businessmen tend to take high risks; some tend to take low risks.   This depends on the income and the choice of the businessmen. So, you must decide your own preferences.  Every person wants to become rich in the Forex market to improve their daily lifestyle. But people must work hard to secure their deposit and increase the account money to do the trade for a long time. Stick to your Trading Hours  Spending all day in front of the screen can lead to burnout and bad decision-making.  Especially if you are new, and already on edge with insecurity regarding your decisions.  Instead, create your trading schedule based on your strategy and the currency pairs you are trading.   Usually, taking trades during peak market hours when there is more participation generates better opportunities.  And once that’s done, stick to it! Taking random trades at odd hours will mostly lead to impulsive decisions, costing you money.  Control Your Emotions Even the best strategy won’t help you if emotions interfere. Fear and greed are known to be the biggest pitfalls for traders. You should structure your trading by automating a part of it to avoid emotions. For example, you can use automatic stop-loss and take-profit orders so that you don't get taken into deciding under pressure in a volatile market. Before you begin a trading session, assess your state of mind. Are you feeling stressed or preoccupied? Such emotions may impair your judgment. Regular intervals and mindfulness exercises will help you keep your trading instincts intact.  Final Note Trading is a journey that can last you for a lifetime. Plus, act as a passive source of income when you are monterily in your roaring 20s. It's not a very popular opinion, but calculated trading can also help you become more responsible with your income. It gives you a fair idea of where you shouldn’t spend your money, and what is the ‘right place’ to invest. While the idea of ‘buying low and selling high’ might sound exciting, you should also be aware of the reality. Profitable trading is more difficult than just buying stocks when the price goes down or selling when the price goes up.  A currency trader needs to have a big-picture understanding of the economies of the various countries and their interconnectedness. Especially how their business and inflation rate would affect the company you are currently interested in investing in. Consistency is the name of the game. Test your strategy under different market conditions and tweak it if necessary. In time, you will be able to yield comfortable growth on your trading account.  Read Also: Capex Trading Platform Review How businesses can use stock trading Forex Trading Wisdom: Talk Yourself Out of Bad Trades

READ MOREDetails
Insurance Leadership Development

Why Growing Insurance Agencies Eventually Hit A Leadership Ceiling

Many insurance agencies reach a point where growth stops feeling straightforward. At five staff, the business often still feels tightly connected. Communication happens naturally. Everyone knows the clients, the workflows, and the day’s priorities. Agency owners remain directly involved in almost every important conversation, from renewals to staffing decisions. Then the business grows. A few more producers are hired. Servicing teams expand. Administrative support increases. Revenue climbs steadily. On the surface, the agency appears successful. Yet somewhere between five and twenty staff, a different challenge begins to emerge. It is no longer just a sales problem, a hiring problem, or an operational problem. It becomes a leadership problem. This transition catches many agency owners off guard because the style of insurance leadership development that helped build a smaller agency often becomes less effective as complexity increases. The issue is not capability. Most agency founders are highly driven and deeply knowledgeable about insurance. The problem is that leading a small team and leading a growing organization require fundamentally different approaches. Why Small Agency Insurance Leadership Development Feels Easier In smaller insurance agencies, insurance leadership development tends to happen informally. The owner can overhear conversations, spot issues quickly, and step into problems before they escalate. Team members rely heavily on direct access to leadership for decisions and guidance. Processes remain flexible because the business is small enough to adapt in real time. This environment creates speed and closeness. It also hides structural weaknesses. Many agencies operate successfully for years without clearly documented workflows, defined accountability structures, or formal communication systems because the owner acts as the central coordinator holding everything together. At five staff, this can work surprisingly well. But at fifteen staff, it often becomes exhausting. The Founder Bottleneck Starts Quietly One of the first signs of the insurance leadership development gap is that agency owners become the bottleneck without fully realizing it. Every important decision flows through them: client escalations producer questions servicing approvals hiring decisions workflow problems operational disputes renewal complications The business becomes dependent on constant leadership intervention. At first, this can feel manageable. Owners often take pride in being deeply involved. Over time, however, the workload becomes unsustainable. The agency grows faster than the owner’s capacity to personally coordinate everything. This creates delays throughout the organization. Staff waits for approvals. Communication slows down. Decisions become inconsistent depending on how overloaded leadership feels on a given day. Ironically, growth can begin to reduce operational clarity instead of improving it. Why Communication Complexity Expands So Quickly The communication demands inside an insurance agency increase dramatically with each additional hire. A five-person team has relatively simple coordination needs. Information flows naturally because everyone interacts constantly. A twenty-person team operates very differently. Departments begin forming. Producers manage different account types. Service staff juggles larger client loads. Insurance leadership development can no longer rely on informal conversations to maintain alignment. Without stronger communication structures, agencies often experience: duplicated work conflicting information inconsistent client experiences confusion around ownership missed follow-ups internal frustration between teams What makes this particularly difficult is that many insurance professionals are highly independent by nature. Producers especially tend to develop their own communication habits and workflow preferences over time. As agencies grow, those inconsistencies become harder to manage. The Emotional Shift Few Agency Owners Expect There is also an emotional side to this transition that rarely gets discussed openly. Many agency founders start their businesses because they enjoy direct client relationships, problem-solving, and building something personal. As the team expands, their role gradually shifts away from hands-on insurance work toward people management and operational leadership. Some owners struggle with this transition more than they expect. And, rather than working in the direction of clients and growth plan, they are dedicating more and more time in resolving tension within the team. Additionally, they give their all in doing the following things: Clarifying different roles and responsibilities. Analyzing performance issues. Handling failures of internal communication. It can be frustrating because the work seems less relevant to the reasons they first joined the industry. Sometimes, in the face of insurmountable complexity, leaders simply maintain the behaviors typical of running a small team. That is where operational strain begins to accelerate. Why Accountability Becomes Harder During Growth In smaller agencies, accountability is usually obvious. Everyone can see who is handling what. Problems are visible immediately. Performance conversations happen naturally because teams work closely together. As headcount increases, accountability becomes less clear unless leadership intentionally structures it. This is where agencies often experience: Missed deadlines Stalled renewals Servicing confusion Inconsistent producer follow-through Uncertainty around decision ownership Many growing agencies operate in what management consultants sometimes call “organisational grey zones.” Staff is technically responsible for tasks, but nobody has clear visibility into whether those tasks are actually being completed consistently. Over time, this creates operational drift. The business still functions, but less predictably than before. The Risk Of Promoting Great Producers Into Weak Managers Another common issue appears when agencies begin creating leadership layers for the first time. Strong producers or account managers are often promoted into supervisory roles because they perform well operationally. Unfortunately, technical skill does not always translate into leadership capability. Managing people requires: communication clarity coaching ability emotional intelligence conflict management delegation skills operational discipline Without proper support, newly promoted managers can become overwhelmed quickly. Some continue handling their old workloads while attempting to lead teams at the same time. This usually creates stress for everyone involved. The agency owner remains overloaded because middle management lacks confidence or authority. Team members become unclear about reporting structures. Operational consistency weakens further. Leadership gaps often emerge not because people lack talent, but because the business outgrows informal leadership structures faster than expected. Why Operational Systems Become Insurance Leadership Development Tools At a certain stage, operational structure stops being just an administrative concern. It becomes a leadership necessity. Growing agencies increasingly rely on: documented workflows shared visibility across teams standardized communication processes clear task ownership centralised reporting performance tracking systems This is one reason many firms begin investing in stronger management systems for insurance agencies as headcount expands. The goal is not simply efficiency. It is creating operational clarity that allows leadership to scale beyond one person’s direct oversight. Without that structure, agency owners often remain trapped in reactive management cycles where every problem still flows back to them personally. The strongest systems reduce confusion before it spreads across the organization. Culture Starts Changing Faster Than Leaders Realize One overlooked consequence of growth is cultural drift. Smaller agencies often operate with strong personal relationships and shared expectations. As new hires join quickly, culture becomes harder to maintain through proximity alone. New staff members may interpret priorities differently. Communication styles become inconsistent. Departments develop separate habits and assumptions. Without intentional leadership, agencies can slowly lose the sense of cohesion that once made the business feel connected. This matters because insurance remains deeply relationship-driven, both internally and externally. Teams that operate in silos eventually create inconsistent client experiences. Strong leadership during growth requires more than operational oversight. It requires actively shaping how teams communicate, collaborate, and make decisions as complexity increases. The Agencies That Navigate This Stage Best Usually Adapt Early The agencies that move successfully from small teams into larger organizations tend to recognize one important reality early: Growth changes the leadership job entirely. The owner can no longer operate purely as the top producer, chief problem solver, or central communication hub. Sustainable growth requires: delegation. operational clarity. stronger middle management. shared accountability. structured communication systems. proactive insurance leadership development. Most importantly, it requires letting go of the idea that the business can continue operating informally forever. The leadership gap between five and twenty staff is not really about company size. It is about complexity. Agencies that adapt early usually emerge stronger, more stable, and better positioned for long-term growth. Those who delay the transition often find themselves trapped in constant operational firefighting while wondering why success suddenly feels harder to manage than expected.

READ MOREDetails