Published on: 28 June 2021
Last Updated on: 03 January 2025
Your health is an essential preference in your life. You want to be sure you are happy, healthy, and able to do whatever you want throughout your day. Sometimes, this may require visiting a specialist or seeing certain doctors to be sure you are under the best health insurance covers.If you've been experiencing back pain, headaches, or neck pain, you may need chiropractic care. These specific doctors deal with disorders of the musculoskeletal system and help you recover from many different things. Whether you have general back pain, are recovering from a sports injury, or just need somebody’s adjustments, a visit to chiropractic care may help with that. Seeking specific medical care can sometimes be a stressful experience, especially if you are worried about the cost. When you are under good health insurance covers, you do not need to worry about the cost of the treatment in medical care.
4 Things To Understand Your Health Insurance Coverage
You know your health insurance covers regular checkups and doctor's visits of that nature, but how can you be sure if you're covered for a chiropractic treatment plan? Start by checking with your insurance company and looking for specific practitioners. There are ways to check your health coverage and figure out how you're going to pay for your chiropractic care. Here are four things to understand your health insurance nature.
1. Research The Most Comprehensive Health Care Plans
It all starts with picking out the right health care plan. You can compare plans online and see the complete layout of each option. Find a health insurance coverage plan that fits your lifestyle and will benefit your overall health. You can research different providers, what your premiums include, and how you can customize your coverage. While many health plans are provided by your employer, you can still pick and chose some of the human services you need. Or, if it's your first time on the health insurance marketplace, you can use online tools to explore health insurance options. That's the best way to compare prices and coverages to get an insurance plan that will include the chiropractic care you need.
2. Look For Providers In Your Network
If you are unfamiliar with how health insurance plans work, you need to know about in-network and out-of-network providers. When you go to a specialist that is in your healthcare network, you will usually have all or most of those costs health insurance covers. As you are looking for a chiropractic office, start by checking in with your insurance website to find the specialists that belong under your health insurance coverages.For example, residents of Governor's Park, CO, have a great office nearby, so when they search for"chiropractor Lone Tree, CO," they won't be disappointed. These providers offer everything you need for your family care, from chiropractor appointments to massage therapy, acupuncture, and even physical therapy. Help your overall wellness with these services.
3.Ask For Referrals From Your Doctor
Are you confused about what chiropractors are considered in-network? Luckily, most primary doctors can easily access that information. When you speak to your family doctor, mention that you've been considering chiropractic services. They can then direct you to a local location that will be covered by your insurance. In fact, many chiropractic offices need a referral before they can start on your treatment plan. The referral simply lets them know your unique needs from the perspective of another medical professional. Always check with your health insurance covers first. The insurance company will let you know if this is a custom orthotics and chiropractor practice that's covered by your insurance plan.
4. Check If You Have Full Or Partial Coverage
While your health insurance plan may cover some chiropractic adjustments, you need to be sure to read the fine print. There may be exclusions or specifications you need to pay attention to. Be aware that your health insurance covers may not pay for the entire treatment, and you may have some out-of-pocket costs, even if you are covered.
Conclusion
The health insurance covers and the plans are prime checking factors before you are availing the services from the popular health insurances. These fours are the best way to analyze the nature of your health insurance plannings and facilities. Most of the insurances are covering all medical costs, but connections are significant. If you do not check the connection medical facility, you may lose the facility your insurance company is offering you.Read Also:
Content Rally wrapped around an online publication where you can publish your own intellectuals. It is a publishing platform designed to make great stories by content creators. This is your era, your place to be online. So come forward share your views, thoughts and ideas via Content Rally.
Staking cryptocurrency is a growing trend since it allows individuals to generate passive income from their existing cryptocurrency holdings.
Making money in the crypto space can be done in several ways. You can join in DeFi and stake your cryptocurrencies, acquire and keep coins with the expectation of price appreciation, or trade on price speculation via crypto CFDs.
In this post, we will define staking and walk you through the steps necessary to begin staking your own coins.
What Is Crypto Staking? How Does Staking In Crypto Work?
By "locking up" assets to maintain the integrity of a cryptocurrency network, "staking" allows users to receive a passive income from their cryptocurrency holdings without ever having to sell their coins. Investing in cryptocurrency through staking is equivalent to putting money into a high-interest savings account.
Staking allows cryptocurrency networks to obtain consensus on the status of transactions via a proof of stake mechanism, with the tokens themselves acting as a kind of internal security rather than the computer power and electricity consumed by the network.
This is demonstrated by the success of proof-of-stake cryptocurrencies like Cardano, Solana, and Polkadot in the cryptocurrency market. These networks are able to process a high volume of transactions with low transaction fees because of the various staking mechanisms they employ.
Blockchain infrastructures benefit from this because they become more adaptable, affordable to users, and eco-friendly. Besides improving cryptocurrency's safety, scalability, and efficiency, staking lets its owners make passive revenue.
To maximize their returns, many long-term holders are taking advantage of staking rewards. Staking, however, has some negatives, such as a reduced ability to sell assets swiftly in the event of a market downturn.
The network chooses validators according to the number and age of tokens they have staked. Staking more tokens for a longer period of time increases the likelihood of getting chosen as a validator.
Users that have a lesser portion of tokens have a decreased likelihood of contributing to the network's security and earning incentives as a result of their participation. Because of this, users with a lower stake make use of staking pools so that they can take part in the network.
Staking Pool Definition
To increase their chances of being chosen to validate blocks and receive block rewards, cryptocurrency network users can form staking pools by pooling their funds with other users.
Those who have stakes in the pool receive a proportional share of the block reward based on the sum of stakes they own. Staking pools, therefore, often result in lower payouts than individual staking. In contrast to the reliable and predictable payouts from staking pools, solo staking involves a significant investment in the crypto network.
Operators of staking pools, typically cryptocurrency exchanges, are in charge of maintaining the network's validator nodes. Participants in the pool are obligated to store their funds at a predetermined public blockchain address. The pool has a nominal price for this convenience.
Other options enable users to stake money from their wallets directly into pools. Cold staking is one method that allows users to participate in pools while still using their hardware wallet.
Users who don't feel comfortable managing and running their own node but still want to contribute to the security of the cryptocurrency network can do so through staking pools.
Why Is Staking Limited To Some Cryptocurrencies?
Whether or not a cryptocurrency network supports staking depends on the consensus process used.
Many cryptocurrencies, including Bitcoin and Litecoin, are not stackable because of the consensus method they employ. The double-spending issue that plagued early attempts with digital currency is resolved by crypto networks thanks to their consensus processes.
These consensus procedures are resilient in the face of opposition because of the careful economics they employ. The economics of the first cryptocurrency networks relied on mining, the mechanism through which nodes competed to solve cryptographic challenges with computational power.
Tokens and transaction fees are awarded to the node that verifies the right set of transactions and solves the cryptographic issue first. Bitcoin mining has come under fire due to concerns over its impact on the world's energy supply.
Later, in 2012, Peercoin's developer presented the notion of staking as a solution to the problems with the proof of work consensus mechanism. By risking their tokens, nodes demonstrate their support for the right set of transactions without having to solve complicated cryptographic challenges. Staking is only possible in cryptocurrencies because only they use this particular consensus methodology.
However, in order to attain consensus, several cryptocurrencies use a hybrid approach, combining proof of stake with proof of work. Bitcoin and Litecoin are examples of very straightforward cryptocurrency networks that can function adequately using proof of work.
Moreover, proof of work is notoriously time-consuming and expensive, making it unsuitable for use in cryptocurrency networks like Ethereum.
How Are Crypto Staking Rewards Calculated?
Crypto staking calculators are utilized to determine the value of staking incentives. These calculators provide you with an estimate of the amount of interest you will get after the investment period has passed.
Calculators work with the number of tokens invested, the annual percentage yield, and the length of time the tokens are held. Be sure to do the math on the potential winnings from your bets before you place them so that you can pick the solution that works best with your goals.
What Are The Benefits Of Crypto Staking?
As is the case with all different kinds of investments, there are potential downsides as well as potential upsides. Find out more about the benefits of staking cryptocurrency below:
It validates financial transactions with a little amount of energy consumption.
A cryptocurrency network can have its own internal security without having to rely on third-party hardware.
Provides customers with the ability to generate passive income from their cryptocurrency holdings.
It contributes to increasing the scalability of cryptocurrency networks.
Provides an incentive for users to contribute to the safety of blockchains by reducing the required investment in their tokens.
Is Staking Crypto Safe?
There is some risk involved in staking, despite the fact that it is a revolutionary and relatively simple technique to generate passive income from your crypto holdings. Before staking their coins, investors need to be aware of certain risks, including the following:
Low Liquidity
When staking cryptocurrencies with a lesser market cap than Bitcoin or Ethereum, users frequently run the danger of being unable to sell their tokens once the staking time has ended. Choose a cryptocurrency that has a high level of liquid market activity and one that supports staking in order to reduce the impact of this risk.
Lockup Periods
Users will not be able to access their tokens while they are participating in the staking process since several staking protocols have lockup periods. You will not be able to sell the staked token in order to reduce your losses in the event of a personal financial crisis or if there is a significant reduction in the value of the staked token.
Alternatively, you may have to pay a high price to get at your tokens, reducing the number of tokens you have staked. Staking tokens without lockup periods is one way to deal with this.
Validator Limitation
In order to enhance their likelihood of successfully validating blocks, certain protocols mandate that validators keep their nodes online and operational at all times. In addition, validators need to exercise extreme caution whenever they operate a node.
If validators make a mistake and include invalid transactions by accident or if they default by going offline, they run the risk of having their staked tokens wiped out, which could include the tokens of individuals who are associated with that node.
Protect yourself from this by either becoming a validator by learning how to host a node or by staking your tokens with a trusted staking pool.
Conclusion
If you have cryptocurrency that you may stake and you do not have any immediate plans to trade it, then you should consider staking it. You won't have to put in any effort at all, but your cryptocurrency holdings will grow as a result.
What happens if you don't currently possess any cryptocurrency that you can stake? Researching cryptocurrencies that support staking is something you should do because of the potential returns.
There are many platforms that provide this service; nonetheless, it is important to determine whether or not each cryptocurrency represents a sound financial investment. You should only buy a cryptocurrency with the intention of staking it if you are also convinced that it is a suitable long-term investment.
The proof-of-stake system has proved useful, not just for cryptocurrencies but also for investors in crypto assets. Proof of stake is a method that can be utilized by cryptocurrencies to facilitate the processing of a high volume of transactions with a low associated cost.
Since you now have a better understanding of staking, you can begin looking into cryptocurrencies that have this feature.
Read Also:
Why Entrepreneurs Should Pay Attention To Cryptocurrencies In 2021
Is 2021 The Most Critical Year For Bitcoin And Other Cryptocurrencies?
The Future Of Digital Currencies: 7 Things We Can Expect In 2022
Before entering into marriage, you and your soon-to-be lifetime partner should talk about finances. Both of you might have different ways of handling your finances.
Settling down and starting to grow a family is one big responsibility that both of you will share. One may be frugal and minimalist, while the other is the opposite. Your differences, if not taken seriously, like by discussing it, might cause a collision.
Just let me share one fact about what happens in marriage nowadays. Few are getting married. Many are getting divorced. And according to Forbes, one of the factors why couples end up divorcing is money issues. Unsettled issues!
It's not the main factor, but somehow, it contributes tension to the couple. And we don't want to let that happen to you. This article aims to help you understand what a couple should do in creating your budget.
Take this opportunity to know what couples should do in handling money. These best-picked tips will guide you in building your budget.
Vital Tips For an Effective Budget-
Communicate at all times:
Discussing financial matters is vital, and it's the only way to know each other, especially in handling money.
Let's face reality. Not all couples have the same spending habits. One might want to save more and choose to live a simple lifestyle, while the other might want the opposite.
As you can see, managing your finances contrasts with the other. With that scenario, both of you might encounter some financial struggles while building your budget goals.
Through proper communication, you can set things up with an open mind. But both should adjust each other's expectations. This way, you can organize everything and meet one's goal.
Remember, this isn't a simple game to win. It's a real-life game that both should work together as one.
Categorize your budget:
If both of you feel like your goals are somewhat overwhelming, you have to remember that you can only eat an elephant one bite at a time.
By simply categorizing your budget, you can have a more exact path to follow. You can see which to prioritize and which is more necessary. Do it one step at a time.
As you continue to discuss things, one should jot down everything. This way, you won't miss or forget some information or idea.
Identify your household needs:
Both should identify your household needs. This way, it will become easy for you to categorize them. List them down. Afterward, you order them to either mandatory expenses, significant, nice, or unnecessary.
Don't forget to include your existing debts on your list. May it be a mortgage loan, credit card, other outstanding debts, car loans, utility bills, food, and other different personal needs.
After listing things, you can now identify which category it is.
Mandatory expenses and significant ones should be your top priority. The rest will be considered as your minor focus.
You might be wondering what mandatory expense is? In layman's terms, mandatory means something that obliges you to perform. That means "mandatory expenses" are something that obliges you to settle.
For instance, debts that should be settled fall to mandatory expenses. Whatever type of debt it is, it will be considered mandatory spending.
Settling debts might be overwhelming. Why not consider paying your debts in full using a personal loan from a licensed money lender Tampines? It's a form of debt consolidation. It merely means combining your debts into one.
For example, you consolidate all your credit card debts and pay them using a loan from moneylender woodlands. You settle your debts in total, with lower interest and one monthly payment.
If there's something you are paying because you need it, you can categorize it as a pressing need.
Important or significant things refer to your basic needs. Foods, clothing, water, electricity, internet connection, and the likes are your basic needs.
Nice things give you fun and convenience, but not that important. For example, car accessories, upgrading or changing phones, buying too many dresses. Everything's look nice but not necessary.
Unnecessary things are simply those that don't have value. For instance, you purchased an online subscription that you seldom use for leisure. It's a total expense that you don't benefit anything. And it only cost you money.
Spending money to buy trendy things, eat at a restaurant, and travel around is not bad. As long as you know to discipline yourself. You can never deprive your happiness in reaching your goals.
But if you want to achieve your financial goals faster successfully, you have to be patient. Always remember that it takes strong commitment and determination to do it. Saving more, spending less will help you a lot.
Set money goals:
Setting goals means taking in-depth planning. It is about creating a path towards your goal, guiding you on how to achieve it.
Achieving your money goals is not impossible as long as you make a well-thought plan. To make it happen, both of you must cooperate with your plan.
Visualize what both of you want to have. Both should be specific.
Let’s say you are dreaming of buying a condominium property. In what location? How big should it be? Would it be a two-bedroom or three-bedroom unit? Such questions show what particular property you dream of having.
Aside from being specific, you evaluate whether it is realistic and achievable in your current state. Your partner dreams of having a sports car. The question is, is it realistic to get such a thing based on both financial capabilities?
The next thing you must consider is the time-frame. Home property is expensive and needs a considerable amount of money. If you aim to buy one, you have to set a timeline.
Just say, after two to three years, you will buy your dream property for your family. Within those three years, both will have to work hard and commit to saving a part of your income until you reach your specific goal.
The mentioned tips above will be the most thoughtful way to start building your budget goals. Otherwise, the case can probably push you to sacrifice valuable things. You and your partner should evaluate your money flow before you decide.
Determine how much you earn:
The next thing you do after setting your goals is to determine how much earning you have. There are types of income that we make - gross and net income. Among these two, net income is what you are going to use in creating a budget.
Gross income is a sum of money before your taxes and deductions. In contrast, the net income is your take-home pay.
The question is, are both of you work as a salaried employee or not? If you are an employee paid hourly, your income would likely be stable.
But if you work seasonally, or you are self-employed, that means you earn irregularly. That said, you have to track your income section monthly.
Track your spendings by having a meeting:
You both need to track your spendings. You can do it daily, weekly, or monthly. But for couples who have just begun to create their budget goals, it is recommended to do it every day. You can eventually do it weekly or monthly.
You talk about where your progress is towards your budget goals. You check every spending you take on different categories and manage what's left.
You can do less work by using some financial apps exclusively designed for couples to organize and track finances. It gives convenience and, at the same time, can make your meetings shorter and more effective.
The Grand Debate – Joint or Single Account
Any newlywed couple's financial choice is whether to open joint or separate accounts.
Now, many might love the idea of sharing finances such closely, or while others might run away from the idea.
There is not wrong or right about having a savings account. It is all about advantages and disadvantages based on your relationship with money and each other.
Some like more autonomy when it comes to financial reasons!
However, you should decide upon assessing both the pros and cons of the matter!
When it Comes to Joint Accounts
Many couples opt to open joint accounts as a way to keep their finances simple. With a joint account, each partner puts their income into one account, making it easier to manage household bills and expenses and work together to reach their financial goals.
It also promotes transparency and trust, and as everything is out in the open, you and your partner will both be on the same page when it comes to spending money.
Joint accounts can also make it easier to achieve long-term savings goals such as buying a house or traveling.
However, you will need to communicate well because if you have different spending priorities, this could cause tension.
In terms of Separate Accounts
On the other hand, keeping separate accounts can help partners feel more in control of their finances. This is especially true if one tends to spend more on hobbies or interests.
With separate accounts, both individuals agree on how much money they will contribute toward shared expenses (like rent, groceries, and utilities) and what they’ll keep for themselves.
While this approach allows for independence, it requires open lines of communication and clearly defined expectations.
Are you ready to begin your financial journey?
Creating a budget has to be undergone through in-depth planning. Start-ups aren’t easy.
Both of you might face financial challenges along the way. However, with concrete planning, if both are committed to achieving the goals, nothing is impossible. Follow what you should do, focus, and get it one by one.
You should also consider discussing bank accounts, and other matters early on.
In the end, some couples find that sharing a hybrid approach works best for them.
This is where they have one joint account for shared expenses and then each maintain a separate individual account for their own personal spending.
This way both individuals get some level of independence with their finances while still maintaining financial transparency.
The most important part here is to communicate on a regular basis and adjust along the way to ensure both individuals’ needs are being met and goals are being achieved.
Read Also:
Make Your Savings Goals Come True with Gold
Eight Essential Tips For Getting Out Of Debt
The Importance Of Saving: The Bedrock of a Bright Financial Future
As people hit their 40s, many of them start thinking about the future, especially their retirement. It's a time when they begin to contemplate the quality of life they want to enjoy once they bid farewell to the daily grind of work. While envisioning leisurely days and fulfilling experiences during retirement is exciting, it's crucial to remember that good health is the foundation for a happy and healthy retirement. This article will delve into the importance of maintaining good health in midlife and explore how it intersects with the financial side of retirement planning.
The Role Of Health In Retirement Planning
When it comes to planning for your golden years, health should be a top priority. After all, what good is a hefty retirement savings if you're not in good health to enjoy it? This is where the expertise of a retirement advisor can prove invaluable. These professionals specialize in helping individuals like you prepare for retirement by taking into account various factors, including your health.
Prioritizing Your Health
In your 40s, it's the perfect time to take stock of your health and make necessary adjustments. Regular exercise, a balanced diet, and proper stress management become even more critical. These habits not only improve your current well-being but also set the stage for a healthier future.
Healthcare And Insurance Planning
One of the key aspects of health in retirement planning is understanding the financial implications of healthcare. Medical expenses can quickly eat into your retirement savings if you're not adequately prepared. This is where a financial advisor with expertise in retirement strategy can be your guiding light.
Retirement Income Planning
Retirement income planning is an essential component of securing your financial future. It involves estimating your retirement expenses, including healthcare costs, and then determining how to generate income to cover those expenses. This process may involve various income sources, such as pensions, Social Security, and personal savings.
Retirement Planning Services
Many financial institutions offer specialized Retirement Planning Services to help you navigate the complexities of planning for your retirement years. These services can provide you with personalized strategies tailored to your unique financial situation and goals.
The Cost Of Healthcare In Retirement
Here's a closer look at the financial aspect of healthcare planning for retirement. Healthcare costs tend to increase with age, making it a significant consideration in your retirement budget. Here are some key factors to keep in mind:
Medicare Coverage
Most Americans become eligible for Medicare at age 65, which can provide essential coverage for hospital stays and medical services. However, Medicare doesn't cover all healthcare expenses, and you may need supplemental insurance to bridge the gaps.
Long-Term Care
Another critical aspect of healthcare planning is considering the potential need for long-term care. Long-term care insurance can help protect your assets in case you require assistance with activities of daily living, such as bathing or dressing.
Prescription Medications
The cost of prescription medications can also add up in retirement, especially if you have chronic health conditions. It's essential to budget for these expenses and explore options like Medicare Part D for prescription drug coverage.
Building A Retirement Nest Egg
To ensure a happy and healthy retirement, it's crucial to start building a robust retirement nest egg in your 40s. Here are some strategies to consider:
Maximize Retirement Account Contributions
Take full advantage of employer-sponsored retirement plans like 401(k)s and individual retirement accounts (IRAs). The contributions you make in your 40s can grow significantly over the years thanks to compound interest.
Diversify Your Investments
Work with a financial advisor to create a diversified investment portfolio that aligns with your risk tolerance and retirement goals. Diversification can help protect your savings from market volatility.
Create An Emergency Fund
Life is unpredictable, and unexpected expenses can arise. Building an emergency fund in a high-yield savings account can provide a financial safety net during retirement.
Pay Down Debt
Reducing your debt load before retirement can free up more of your retirement income for leisure activities and healthcare expenses.
Staying Active And Engaged
While financial planning is crucial, it's equally important to stay active and engaged in life during your 40s and beyond. Maintaining a robust social network, pursuing hobbies, and staying mentally active can contribute to your overall well-being.
Conclusion
In your 40s, the journey to a happy and healthy retirement begins with prioritizing your health and making sound financial decisions. Seek guidance from a professional like a retirement advisor or financial advisor who specializes in retirement planning strategies. Remember that maintaining good health is the cornerstone of enjoying your retirement to the fullest, and proper healthcare and insurance planning are integral parts of your financial strategy. By taking proactive steps now, you can set yourself on the path to a fulfilling and prosperous retirement, both financially and in terms of your overall well-being.
Read Also:
Smart Ways to Invest in Gold
How To Start Your Investor Journey: 5 Credible Options To Explore
What Investors Should Know about Investment in Gold and Silver Assets
 It all starts with picking out the right health care plan. You can compare plans online and see the complete layout of each option. Find a health insurance coverage plan that fits your lifestyle and will benefit your overall health.
You can research different providers, what your premiums include, and how you can customize your coverage. While many health plans are provided by your employer, you can still pick and chose some of the human services you need. Or, if it's your first time on the health insurance marketplace, you can use online tools to explore health insurance options. That's the best way to compare prices and coverages to get an insurance plan that will include the chiropractic care you need.
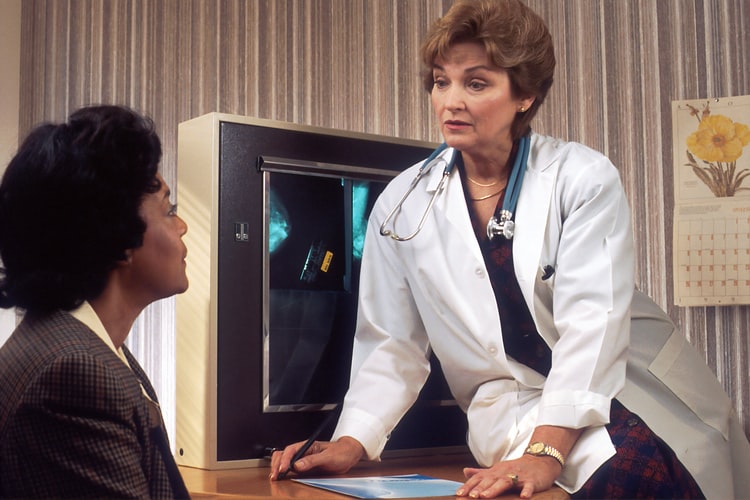 Are you confused about what chiropractors are considered in-network? Luckily, most primary doctors can easily access that information. When you speak to your family doctor, mention that you've been considering chiropractic services. They can then direct you to a local location that will be covered by your insurance.
In fact, many chiropractic offices need a referral before they can start on your treatment plan. The referral simply lets them know your unique needs from the perspective of another medical professional. Always check with your health insurance covers first. The insurance company will let you know if this is a custom orthotics and chiropractor practice that's covered by your insurance plan.
 While your health insurance plan may cover some chiropractic adjustments, you need to be sure to read the fine print. There may be exclusions or specifications you need to pay attention to. Be aware that your health insurance covers may not pay for the entire treatment, and you may have some out-of-pocket costs, even if you are covered.