









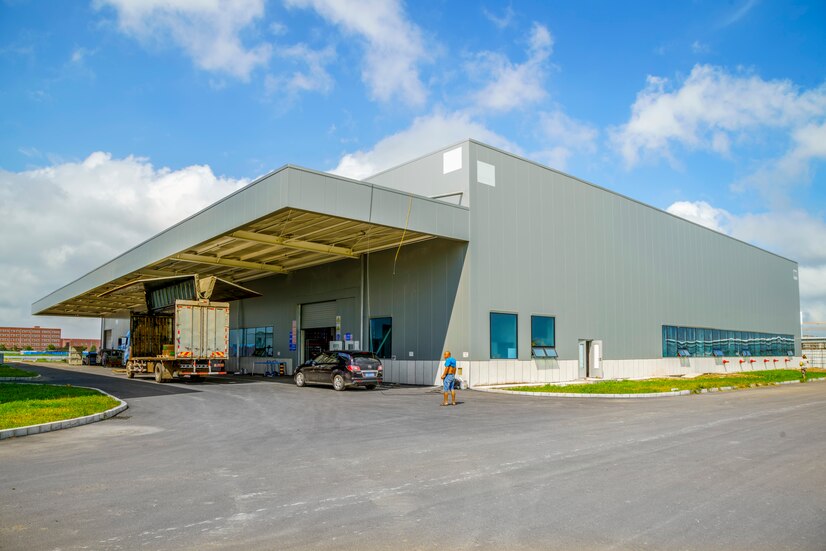
What Does It Cost To Lease Office Warehouse In Woodbury?

Published on: 24 October 2023 Last Updated on: 06 March 2024
Lease Office Warehouse In Woodbury
Estimating the cost of leasing space in a business building could appear simple at first. Following your team's decision to rent a commercial facility, you negotiate the terms and price, sign the lease, and vacate the property. As it happens, it takes diligence and the assistance of a tenant broker to properly comprehend a business lease. Which party, you or the landlord, will be in charge of paying the insurance and property taxes? Who is going to cover the utility bills? Who will pay for the costs of upkeep? You must be clear about the type of business lease that you are signing to get the solutions to those crucial questions.

Getting Started On Leasing Warehouses…

When leasing out office space, a landlord has a variety of business property lease options at their disposal. You will be more savvy during any Woodbury office warehouse for lease negotiations, and your firm will be able to better manage monthly spending if you are aware of the variations between each form of business lease. Let us go over the various kinds of leases for commercial real estate so you can prepare for the terms and know how to bargain for a better deal. The following lists typical descriptions for each form of lease. It is important to remember that each category of lease will provide a renter with an idea of what to expect financially, but it is merely an estimate, and there are no hard and fast regulations. All leases are negotiable. Therefore, the sole means of assurance about the cover costs is to go over the terms of the lease in detail with your leasing broker and lawyer.

Gross Lease Or Full-Service Lease

If you sign a gross lease or, as we popularly say, a full-service lease, you have to pay the basic rent. The additional building costs of an office warehouse, such as insurance, real estate taxes, and maintenance fees, are often covered by the landlord. This usually translates into somewhat high rental prices, but you, the renter, just get one bill that takes care of all the essential office expenditures. Tenants who prefer not to get engaged in the day-to-day operations of an office will find this simpler. Some tenants still have to pay their fair share of running expenditures throughout their base year, though, in some full-service gross leases. This sets a cap on the amount of additional rent that a landlord must provide for tenants' costs. Whatever the case, be sure to carefully review your gross lease to see whether the agreement has any stipulations, such as extra costs. Know more about gross leases here.

Net Leasing Of Office Warehouse

The term "net lease" describes a type of lease for commercial property. Typically, net leases require tenants to cover a certain percentage of the building's operational costs, such as insurance, property taxes, and common area maintenance (CAM) fees. Single, double, and triple net leases are among the types. The amount of financial liability that the landlord transfers to the tenant varies depending on the kind of net lease. Landlords of commercial real estate usually compute the pro-rata portion of running costs for each tenant as follows: They take the overall cost of operation per square meter for all the building's rentable space. Afterward, they distribute that amount among the tenants according to the portion of the building that each renter occupied.

Triple Net Lease

In essence, a three-tier net lease is the reverse of a gross rental. The tenant (you) agrees to cover all running costs of the commercial property. This includes building insurance, property taxes, maintenance costs, and other costs in addition to rent and utilities. Triple net leases often have lower monthly rental rates because the tenant is covering the operating costs. NNN leases frequently have longer terms and include clauses that allow for future rent increases. Some tenants attempt to terminate their leases or renegotiate them when maintenance costs exceed their expectations. Preemptive landlords of any office warehouse will utilize a “bondable” net lease, meaning that it cannot be extended past its expiration date or have the rental rates changed.

Double Net Lease

Rent, utilities, property taxes, and building insurance are all the tenants' responsibilities under a double net lease. However, the cost of structural upkeep (https://ccpia.org/preventive-maintenance-at-commercial-buildings/) for the building is directly covered by the landlord. Base rent is often lower than in other net leases since the tenant bears additional costs. It is common for landlords who rent out office buildings to several tenants. The reason is to equally split the costs of building insurance and property taxes.

One Net Lease

Most tenants have to pay property taxes in addition to rent and utilities under a single net lease. The landlord covers property insurance and upkeep costs. Take care to distinguish between a net lease and a single net lease. A single, double, or triple lease of an office warehouse falls within the category of net leases. 

Read Also:

Ankita Tripathy loves to write about food and the Hallyu Wave in particular. During her free time, she enjoys looking at the sky or reading books while sipping a cup of hot coffee. Her favourite niches are food, music, lifestyle, travel, and Korean Pop music and drama.

View all posts

Leave a Reply

Your email address will not be published. Required fields are marked *

Related

Value Of Your House

How To Learn The Value Of Your House

There are many reasons to want to value a house. A new addition to the family may need additional rooms, a work promotion in another location, or even just time for a change may require the home to be sold. Another reason to value a property is to identify a person’s current financial position. This may be necessary for those starting a business or needing additional finance. How do people learn the value of their houses? Here are three ways. Top 4 Ways Of Learning The Value Of Your House 1. Online Valuation Tools One of the easiest ways to get a valuation is to use one of the many online valuation tools available. They use public data to price your home. These tools use the automated valuation model (AVM). The valuations are based on data retrieved from public records like deeds of ownership, property transfers, and tax assessments. A mathematical formula is also applied, taking data from recent sales in the area. The challenge with relying on AVMs is that they’ll value every property, regardless of the available data, possibly giving an inaccurate value. To effectively use an AVM, do it from a real estate site that also includes a ‘confidence score.’ This value means a professional has checked the result from the AVM and given a score based on how close it is to market value. Any AVM plus a confidence score over 90% can be considered. 2. Comps One of the most common ways to get a current value for a house is to check out recent sales in the same area. Take a look around the neighborhood at comparable homes. These are known in the industry as ‘comps.’ When made public, the results of these sales can be an easy predictor of the values in the area. An ‘apple for apples’ approach needs to be applied here. If the house next door is a little more run-down but has an additional bedroom, that value isn’t a good comparison. If one down the road, with an equal number of rooms, was renovated around the same time, that’s a closer valuation. The way to get the best valuation for your home is to find four comps — two at the higher price range and two at the lower. Go for something that’s somewhere in the middle. Remember that values change quickly; any sale over three months ago may not match the current market. 3. Professionally Appraised The most expensive but arguably the most accurate way to value a home is to get it professionally appraised. These people have seen hundreds to thousands of comparable properties and can give you a correct value. A 2018 survey revealed that ¼ of US homeowners valued their properties this way. Lenders will require an appraisal before approving a mortgage; however, they’ll want it done by their own appraisers. Appraisers may even suggest changes that can be made to increase the property value. A professionally presented pre-purchase appraisal by a reputable appraiser makes it easier for the potential buyer to decide. This is one task that they don’t have to do. Appraisers are independent contractors. They get paid per appraisal; they don’t earn commission and therefore offer unbiased opinions. 4. House Valuation Made Easy Using an AVM is the most convenient way for a person to value their home; however, it’s possibly the least accurate. Spending the time to compare recent sales on comparable properties in the area is a closer way to get a more accurate price. Choosing a value mid-range of these is the best way. Unbiased professional appraisers will provide the most accurate value, but at a cost. Whether using an AVM, checking out local comps, or hiring a professional, there is one surefire way to know the value of a house. The value is whatever someone else is willing to pay for it! Additional: How You Can Increase the Value of Your Home with Stone Veneers 6 Easy Ways To Make Your Home More Appealing To Buyers What Qualifications Do I Need to Have to Get a Home Mortgage?

READ MOREDetails
The Benefits Of Exclusive Listing For Sellers

The Benefits Of Exclusive Listing For Sellers

In real estate, an exclusive listing is a contract between a real estate agent and the owner that grants the agent the exclusive right to sell the property. The realtor will handle the listing for you without submitting it to the multiple listing service. In most cases, the agent will promote the property to prospective buyers and handle everything regarding the sale. The real estate agent will act as the owner’s sole agent. Only one agent will be appointed and expressly authorized to refer the property to potential buyers. On the other hand, in a non-exclusive listing, the owner retains the right to use any number of agents. You need to learn more about exclusive vs. non-exclusive listings and the pros and cons of exclusive listing. In this article, we will focus only on the benefits of exclusive listings for sellers and why this might be the best way for you to sell your home. Let’s dive in! Longer-Term Working Relationship With The Agent You are more likely to develop a genuine working relationship with a single real estate agent. Because your agent will be fully responsible for the sale, they will probably be more motivated to close the deal than open listings. In addition, your agent will put in more effort on your behalf: they will develop personalized marketing strategies to help your property stand out. As your relationship develops, your exclusive agent will make strategic recommendations regarding advertising, marketing, and even renovation strategies to attract higher prices. On the other hand, if your home is listed on the MLS, the public will be aware of your initial price and will be notified whenever you change it. However, with an exclusive listing, the agent can control who can access pricing. High-Quality Offers Your agent will work closely with you to ensure that you get the best price for your property. As mentioned, they may even recommend renovations if they are sure that renovating will pay off by increasing the cost of your property. In addition, they will devise powerful advertising strategies for you to attract higher bids. And exclusive listings typically receive more offers since many believe that non-exclusive listings indicate something wrong, even if there is not. And since people have more trust in an exclusive listing, they are more likely to pay more. In addition, your exclusive agent will spend more time choosing the best clients so they can get the best offer. Also, this eliminates the long negotiation processes with many offers, counter-offers, etc. The agent will put effort into structuring worthwhile offers for you. Read Also: What are the Best Real Estate Seller Leads? Exclusive Listings Attract The Right Buyers Open listing is more likely to elicit interest from more buyers, including Missouri cash home buyers, but this does not guarantee that the buyers are competitive or qualified. In non-exclusive listing situations, agencies keep the important property details private and show your home to as many clients as possible. So, the information about the property will usually be insufficient, resulting in your property being presented incorrectly to the wrong prospects. Even if the property is offered to potential buyers, these qualified prospects are given incorrect information. This is a significant benefit for exclusive listing. Because agents will market the property through their brokerage to a pre-chosen group of prospects, the clients will be more qualified, increasing the chances of a faster sale. In addition, an exclusive listing agreement will give agents the authority to approach the qualified buyers—those most likely to buy the property—openly and systematically. Privacy The reasons for selling a property can vary, from happy ones to reasons like someone passing away or a divorce. Some owners do not want their close ones to know they plan to sell their homes. Also, many people do not want the online world to know their address, the listing, or the selling price. When listing exclusively, your property will not be exposed online or to many agents, which is a significant benefit. In addition, you will gain price and privacy control over the listing. You can work with one agent and have more say over who comes to your property, which could benefit sites under construction or undergoing renovations. Wrapping up An exclusive listing is better suited for owners who prefer a more private selling process and want to control who comes into their property during the sale. Also, an exclusive listing is a perfect option for people who want to work with a single agent since that will give them the confidence that they are fully invested in the sale of their home. However, it is critical to work with a reputable and experienced agent to ensure that your property sells faster and attracts higher-quality prospects who will have better offers for your property. Read Also : How To Sell Your House Fast?! Five Must-Know Tips To Move Your Property! 6 Things You Must Know Before Selling Your Home Buying Or Selling A Home In Seattle?

READ MOREDetails
Buy to let mortgage

Buy to Let Mortgage Explained

A buy to let mortgage differs from a regular mortgage since it is for investors or landlords who buy property to rent out to tenants; not for their residential purposes.  The essential differences that an investor should be aware of can be provided through professional and experienced advice from mortgage brokers in the UK. Some issues linked to the subject are listed below: Buy to Let mortgage in the UK is available to individuals as well as to corporates and companies. However, a BTL mortgage for a company will have to be through a lender who accepts investment through limited companies. Maximum limit:  The amount that can be borrowed is linked to the expected rental income.  Lenders usually require the rental income to be 25-30% higher than the mortgage payment. Deposit: A deposit will be required to be paid to the lender; it is usually 25% of the value of the property (though this can escalate to about 40%). Repayments:  The two ways of paying back the mortgage are explained below: Interest-only mortgage: is self-explanatory and, every month, only the interest on the loan is paid back. This means lower monthly payments, but the loan will have to be paid at the end of the mortgage period. Repayment mortgage: is when both the interest as well as some portion of the loan itself are paid back.  A higher monthly payment will be required, but the advantage is that by the time the mortgage term matures, in all probability, the entire loan would be repaid. Depending on the investor’s capital and budget, advice will be required on the Repayment issue since lenders vary on the repayment requirements. Taxes:  Both Capital Gains Tax and Income Tax are payable on buy to let properties. Capital Gains Tax: The rate is payable dependent on the income bracket of the investor. By adjusting property purchase fees (or even losses from another BTL property), this tax can be reduced. Income Tax: Landlords will not be able to deduct the mortgage interest from rental income.  Instead, the total mortgage interest payment will receive a 20% tax relief.  Fees like council tax or property maintenance charges can be offset if the annual income allowable is exceeded. BTL remortgage: By switching to another deal once the current mortgage is over, a BTL remortgage can sometimes be advantageous as the interest rate can be lower. If a remortgage is required earlier, lenders usually require a minimum time of 6 months after the title deeds are transferred before they will consider this.  However, arrangement fees for BTL are high so remortgaging can be expensive and, since interest rates can fluctuate, the pros and cons will need to be carefully reviewed. Regulation of Buy to let mortgage:  Most of these mortgages are not regulated by the FCA as they are treated as business borrowing. However, Consumer BTL mortgages are handled in the same way as residential mortgages by the FCA, protecting the investor from fraud or incorrect advice.  This type of mortgage is for “accidental landlords” - it is defined as ‘a buy-to-let mortgage contract which is not entered into by the borrower wholly or predominantly for the purposes of a business carried on, or intended to be carried on, by the borrower.’  For example, if the property is bought for relatives to live in, it would be considered as a Consumer BTL mortgage. Legislation:  Investors need a tenancy agreement, outlining the terms and responsibilities of both parties.   The rented property should be kept safe with a fire alarm and all gas and electrical equipment maintained in good condition.  An energy performance certificate should be provided to the tenant.  The tenant’s right to rent should be checked.  The deposit should be protected in a Government-backed scheme. Conclusion:  As in every critical decision, the pros and cons need to be weighed.  In the case of a Buy to Let mortgage, some of them are: Advantages: Demand: With the demand exceeding supply, the rental market is suitable for investors. Capital gain: Although there is a risk with the value of property fluctuating, “brick-and-mortar” has usually survived and increased in value. Income: With the rental trend increasing, the revenue should be an asset. Disadvantages: High fees: Fees, deposits, and admin/legal costs can be increased. Rental voids: There is the risk of having no tenant or a tenant who is problematic with payments. Legal: Keeping in line with the legal requirements can be a big responsibility. Should a BTL mortgage be decided on, just keep in mind that the stamp duty holiday is till 31 March 2021 and so all necessary documentation should be completed well in time if this benefit is to be availed! Read Also: Federal Government and the Subprime Mortgage Crisis They Created 7 Expert Tips In Finding The Best Mortgage Broker In Vancouver Finding the Best Mortgage Lenders to Buy Your Dream House

READ MOREDetails