Published on: 14 August 2020
Last Updated on: 30 January 2026
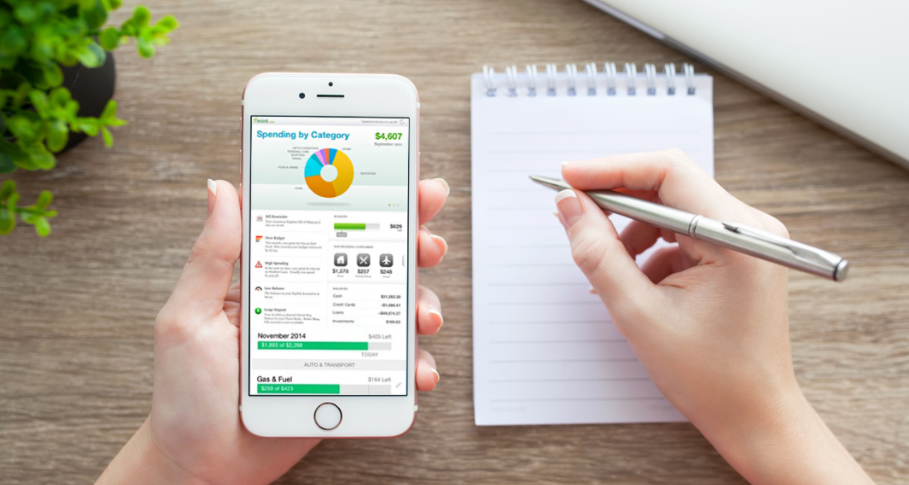
We all have plans and dreams. Nonetheless, to implement them we need financial resources. Todays’ advanced technologies offer a solution to collect the sum we need. So, we shall discuss how to design a great saving application to help people build their dreams into reality, and how you as an owner can succeed as well.
Interested? Let’s get down to business.
Functionalities a money-saving platform should provide
Let’s explore what parameters are critical for users.
# Profiles
It’s pretty obvious that, first of all, a person downloads an app and sets up a personal profile.
Try to keep those processes simple and straightforward. People shall fill in a certain form to specify some information, including the financial one. It’s okay if the account activation takes some time since all customers’ details must be processed and verified carefully. We’re dealing with money issues, thus, everything shall be checked adequately.
# Bank account involvement
A budget framework shall allow the audience to connect their bank accounts. Here the trick is for app owners to cooperate with multiple financial facilities to make such a feature available for every individual.
Moreover, it would be amazing if you also find some solutions for those persons who have no bank accounts and who choose other ways to manage their finances. That approach will enlarge your target audience.
# Possibility to set several goals
Setting goals is a pretty fascinating aspect of an online money resource.
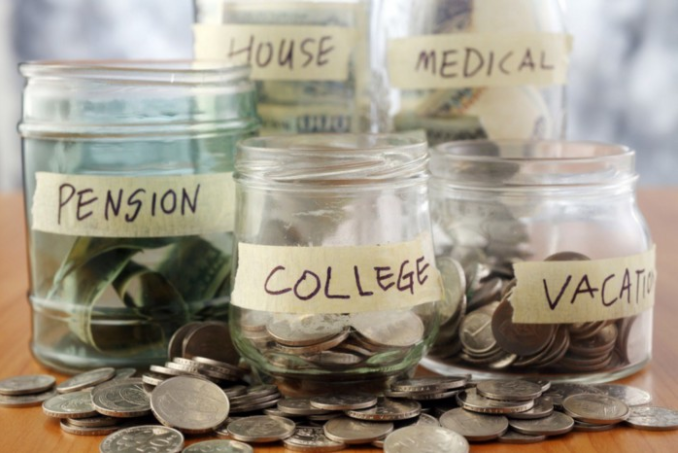
Let’s assume that a person starts applying an online system to save some funds and enforce ceratin plans that demand specific monetary investments. It could be anything, say, university fees or vacations. Thus, a user takes advantage of a financial program and sets a goal to implement a particular plan he/she has. If you want to create a successful app, you shall allow your people to name that plan, put deadlines if it’s required, provide a brief description, etc. That’s how a saving procedure starts.
In most cases, customers have the following goal variants:
travel;
vacations;
gifts purchasing;
nest egg for a rainy day;
others.
Clients will appreciate not being limited to implement only one plan at a time, so individuals shall be free to set multiple goals to realize their desires.
Speaking about allocating funds to specific goals, you could provide a few options here. The thing is that some users would prefer to take the total withdrawing sum and divide it equally between all current plans, while others would rather specify how much money specifically shall be sent to each goal. Just remember to keep your money-saving application customizable.
And after a person manages to save the sum he/she put as a target, budget software shall stop allocating funds to that particular goal, however, the money shall still get sent to other ongoing plans, if any.
# Withdrawal options
Every decent money manager platform shall ensure that its customers can withdraw cash from their accounts when they need to. Moreover, no-fee and no-commission policy will be highly appreciated.
Additionally, it would be a brilliant idea to give your people several options to withdraw money. Let’s say, chatbots could be one of the tools.
Still, the audience needs to be patient, since the processing of such transactions is time-consuming, meaning, individuals will have to wait for the funds to get returned to their main accounts at their requests. However, you could offer specific options for those who can’t wait: say, you might impose a $1 charge to make transfers instant. It’s your call.
# Overdraft-proof
Your clients shall not worry about possible overdrafts, thus, think carefully about how you could protect their accounts. You could ask users to determine the amount of money that must remain on their accounts at any time. In such a way, an online financial service won’t be able to take the money, in case that indicated mark is already reached.
Nevertheless, if some technical issues occur and a money-saving framework withdraws too much, a specific algorithm shall be launched to refund the difference and reimburse all overdraft fees.
Make sure you discuss those options with the development team you hire.
# Unique features
Nowadays, you can find a great variety of diverse financial resources, thus, your objective is to come up with one-of-a-kind parameters to differ from others. Here’s an idea for you.
The reality is that many people have to pay off their debts. Of course, they can simply borrow the amount they need, but it’s better to have several options to deal with those issues. Besides bank loans, people can also resource to online money-saving systems.
Your program can help people deal with their debts. Clients can set specific debt settlement goals, attaching their credit cards to your platform. The process could be completely automated, and a specified amount will be allocated to pay creditors. If you impose special conditions, you can help your customers repay debts faster. Think about it.
Of course, you can brainstorm more to generate other great unique features to bring a wider audience.
# Smart notifications
Individuals will enjoy the possibility to communicate with an application they use, and text messages will do the magic.
Clients need to know their accounts’ statuses, moreover, the messaging notification system can update users on any important news. The audience might want to set the service to receive requests to write off funds, and more.
Additionally, people could use particular code words to launch certain activities. Just be creative, don’t limit yourself, and you’ll find multiple ways to assist your customers making them happy.
There’s one more aspect we’d like to discover this time.
Benefits a saving app shall provide
Every app shall serve to resolve certain problems people have. The below-mentioned ideas are for you to keep the audience pleased with your online solution:
Special bonuses. Why not offer your active users certain bonuses, say, a 2% annual bonus? That would be a nice touch of yours.
Chatbot assistance. A person might need some financial advice, so think about how chatbots could help with that.
Setting numerous goals. As we’ve mentioned earlier, that would be a great idea, since it’ll improve customers’ online experience.
Automatized processes. It’s in your hands to help clients enjoy the saving process: let them stipulate the amount to put aside and make your framework to take care of the rest.
Regular updates. Don’t allow your audience to feel lost, not knowing what’s happening with their accounts. Update them constantly.
Referral bonuses. You could be grateful to people who bring new users to your program by giving them, say, $10 or so.
Keep it simple. Individuals will really enjoy your application if it is user-oriented and appealing.
Web interface. Some people would rather prefer web resources, so consider developing it as well.
We believe our hints and tips will help you consider key aspects of money-saving system development to build a successful and credible service.
Read Also:
Mashum Mollah is the feature writer of Search Engine Magazine and an SEO Analyst at Real Wealth Business. Over the last 3 years, He has successfully developed and implemented online marketing, SEO, and conversion campaigns for 50+ businesses of all sizes. He is the co-founder of Social Media Magazine.
In finance and investment, various tools and strategies are available to help individuals and organizations secure their financial future. Bond insurance is an often overlooked but essential component of a well-rounded financial plan. A trusted Bond Insurance Agency often facilitates it and is crucial in providing stability and protection to investors, allowing them to mitigate risks and achieve their long-term financial goals.
This article explores the importance of this insurance in financial planning and why it should be a part of every investor's toolkit.
I. Understanding Bond Insurance:
Before understanding the importance of this insurance, it's crucial to understand its essence. Commonly referred to as financial guarantee insurance, it's a financial product provided by insurance companies to protect bondholders from the potential risk of issuer default. When investors acquire a bond, they lend money to the issuer, expecting to receive periodic interest payments and the bond's face value at maturity.
Nevertheless, there's invariably a risk associated with this, as issuers might fail to fulfill their obligations due to financial challenges or unforeseen events.
It is a case of issuer default. The insurance company pays bondholders if the issuer fails to make interest payments or repay the principal amount. In essence, it offers a layer of protection that can significantly reduce the risk associated with bond guarantees.
II. Risk Mitigation:
One of the primary reasons it is a vital component of financial planning is its role in risk mitigation. While bonds are generally considered lower-risk investments compared to stocks, there is still a possibility of default, especially when dealing with bonds issued by corporations, municipalities, or other entities. It can help investors feel more secure in their investments, knowing they have a safety net.
Moreover, it can enhance an investor's portfolio by reducing the risk profile. Investors can achieve a better balance between risk and return by including insured bonds in their investment mix. This diversification can lead to more stable and predictable long-term returns, aligning with the goals of prudent financial planning.
III. Income Stability:
Financial planning often involves achieving financial goals, such as retirement and creating a stable income stream. It is pivotal in providing income stability, especially for retirees who rely on fixed-income investments to cover their living expenses.
Retirees can count on a consistent income stream when they invest in insured bonds. Even in the event of an issuer default, the insurance company steps in to ensure bondholders continue to receive their interest payments. This income stability is crucial for retirees who depend on their investments to maintain their quality of life during retirement.
IV. Preserving Capital:
Preserving capital is a fundamental objective in financial planning. It helps investors preserve their capital by minimizing the risk of losing their principal investment due to issuer defaults. This is particularly important for individuals and organizations that cannot afford to take on excessive risks with their capital.
By incorporating insured bonds into their investment portfolios, investors can have greater peace of mind, knowing their initial investment is protected. This protection lets them focus on long-term financial goals without worrying about capital loss.
Summing it Up:
In conclusion, it is an essential tool in financial planning. It offers investors, whether they are individuals looking to secure their retirement or institutions seeking to manage risk effectively, a valuable safety net against the risk of issuer default. It is often obtained through a reputable Bond Insurance Agency, which enhances risk mitigation, provides income stability, and helps preserve capital. It should be a crucial consideration in your financial planning strategy, ensuring your investments are well-protected and aligned with your long-term financial goals.
As financial markets evolve and uncertainties persist, having bond insurance as part of your investment arsenal can provide the stability and security needed to achieve your financial goals. It’s a valuable resource that can help you confidently navigate the complex world of finance, knowing that your investments are safeguarded against unexpected challenges. So, when mapping out your financial plan, don’t forget to factor in the importance of bond insurance—it could be the key to a more secure and prosperous financial future.
Read Also:
How Artificial Intelligence Is Helping Banking and Financial Institutions?
How to Start Your Career as a Financial Advisor?
10 Estate Planning Tips to Help You Prepare for the End
In today's fast-paced world, having a place to call home is a comforting thought. However, ensuring that your home is safeguarded against potential risks is equally important. This brings us to the crucial topic of "home insurance Orillia." In this comprehensive guide, we'll delve into the ins and outs of home insurance, helping you understand why it's an indispensable investment for homeowners in Orillia.
What Is Home Insurance?
Home insurance, also known as homeowners insurance, is a policy that provides financial protection to homeowners in case of unexpected events that damage or destroy their property. It serves as a safety net, offering a sense of relaxation, knowing that your home and belongings are secure.
Home Insurance Types
When it comes to home insurance in Orillia, there are several types to choose from. Each type caters to specific needs and risks. Let's take a closer look:
1. Dwelling Insurance
Dwelling insurance encompasses the physical structure of your house. It consists of the roof, walls, built-in appliances, and even the floors. It’s the most basic form of home insurance and is essential for all homeowners. However, you also need to check out appliance repairs possibilities that may cover under insurance or not.
2. Contents Insurance
Contents insurance safeguards your personal belongings within your home, like clothing, furniture, and electronics. It’s vital for safeguarding your valuables.
3. Liability Insurance
Liability insurance covers you in case someone gets severely injured on your property, and you are found legally responsible. It also covers damage caused by your pets.
4. Additional Living Expenses
This particular insurance assists you in covering living expenses if you are temporarily displaced from your home because of a covered event, such as a fire.
Why You Need Home Insurance in Orillia
Orillia is a beautiful city, known for its picturesque landscapes and serene surroundings. However, even in such idyllic places, unforeseen events can occur. Here's why you should consider home insurance in Orillia:
1. Protection Against Natural Disasters
Orillia is not immune to natural disasters like floods and storms. Home insurance provides coverage for damage caused by these events, ensuring that you can rebuild your life.
2. Theft and Vandalism
Crime can happen anywhere, and Orillia is no exception. Home insurance can help replace stolen items and repair damage caused by vandalism.
3. Peace of Mind
Knowing that your most significant investment, your home, is protected brings a sense of peace. It allows you to focus on enjoying your home and the beautiful surroundings of Orillia.
Read Also:
5 Proven Ways to Reduce Your Home Insurance Rates
How to Choose the Right Home Insurance
Selecting the right home insurance policy is crucial. Here are some steps to help you make an informed decision:
1. Assess Your Needs
Evaluate the value of your home and possessions to determine the coverage you require.
2. Compare Policies
Research and compare insurance policies from different providers to find the one that suits your budget and needs.
3. Read the Fine Print
Pay close attention to the policy details, including deductibles, coverage limits, and any exclusions.
The Bottom Line
In conclusion, home insurance in Orillia is more than just a financial safeguard; it’s a shield of protection for your home and everything you hold dear. By understanding the types of insurance available and the risks you face, you can make an informed decision to secure your peace of mind.
Read Also:
Home Warranty Plans: How To Choose The Right One
The Comprehensive Guide To Property Insurance Toronto
Health Insurance Policy For Family – Here’s A List Of 5 Plans You Can Consider
Signing up for life insurance is usually a great idea. It financially shields your spouse and children in the event of your untimely demise. Also, it’s a win-win situation, at least on most occasions. Your loved ones are financially secure, and you can rest easy knowing they’ll be fine even if you’re not there.
That said, as time progresses and you inevitably age, priorities might shift. You may feel like you don’t want to keep paying for a life insurance policy. For instance, your kids may have finished their education, secured good jobs, and are living pretty stable lives. Or you may find yourself in the middle of an emergency and are simply strapped for cash.
Whatever the case, selling your policy is usually better than resigning yourself. It denotes the value the insurer wants to compensate you. With a life settlement, the term used for selling life insurance – you can secure a much bigger payment.
But how do you go about it? Here are the general steps to selling a life insurance policy.
Tips To Sell Your Life Insurance Policy Easily
As always, selling a life insurance policy has always been a challenge. But with some of the core strategies, you can get the best deal by selling your life insurance. So let us discuss some of the most important tips through which you can manage it here.
1. Find A Good Life Settlement Company
The first step to setting the ball rolling is selecting your buyer. Now, usually, there are three ways to sell your life insurance. The first is to an individual such as yourself. However, this isn’t only difficult to navigate but also makes you vulnerable to all kinds of bottlenecks.
So, you only want to consider the other two. That is an asset management company or life settlement broker. An asset management company, or institutional investor, is a large company that specializes in life settlement investment. So, you essentially sell your policy to them.
A broker, as the name suggests, helps you find an investor, usually an institutional investor, to buy your policy. And they act as an intermediary, negotiating the deal. That said, if you are looking for a good buyer, visit this site.
2. The Life Settlement Company Must Be licensed
The company that buys your life insurance policies is called the life settlement. It must be licensed with the different state departments of Insurance. It will help you avoid any kind of scams. Talk to them and verify their licenses. It must be one of the important steps to sell your insurance coverage.
3. Submit All the Necessary Documents & Information
Once you have found your buyer, either directly or through a broker, the next step is to submit all the required documentation. These include your policy documents and medical records. Now, in the majority of cases, you don’t need to submit your policy-related documents yourself. Rather, you provide authorization to the company you are selling to so that they can get them from your insurance provider.
With everything in order, the underwriting process begins. It is at this stage that your life expectancy, as well as the value of your policy, are estimated.
4. Choose The Best Offer
The next step is the offer negotiation. Basically, the interested buyer, or buyers, submit their offer to you, and you decide whether it is good enough for you. In many cases, the broker will present the best offers only.
Depending on what you are looking for, you can go with the offer presented, or you can forfeit it. That said, life settlements are typically more than the surrender value, which means you will get more money selling your policy to a third party than resigning to what your insurance is ready to pay.
4. Price Based On Policy Value
In general, life settlement companies are mainly interested in high-value policies rather than older ones. Ensure that you have at least a $100,000 life insurance policy. Also, the settlement companies pay you more if you have some health condition leading to a low life expectancy. This kind of policy status earns more if you are selling it to them.
5. Receive Your Lump Sum Payment
Finally, you sign over your policy to the buyer and, in exchange, get the agreed amount as payment. This payment is paid in full, in one lump sum. Once this step is done, you are no longer responsible for premium payments. And when you die, the buyer collects the death benefits.
6. Finding The Reputable Brokers
When trying to find the right broker, you must look out for the most reputable brokers. The best process is to talk with not one but multiple brokers. Not only this, but you must also look for multiple brokers with multiple offers.
Looking for the best quote can only help you get the best offers on sales of your insurance. Reputable Brokers offer you what they have to offer, and nothing is mesmerizing. Hence, play safe and do not run after the offers.
How Much Will I Get from Selling My Life Insurance Policy?
The lump sum cash you get from selling your life insurance policy in a life settlement will be a lot higher than its face value, often four or more times the cash surrender value of your policy. Even so, the precise among typically depends on several factors, including:
Your insurance policy’s premiums
Death benefits
Life expectancy
Therefore, the life settlement company will consider all these to determine your specific payout.
Want To Sell A Life Insurance Policy? Seek Advice From A Reputable Life Settlements Company
The last thing you want is to sell a life insurance policy you have been paying premiums for over a long time for an unfair price in the market. For this reason, you need to find a good life settlement buyer for your policy. Besides advising on your settlement, a life settlement company will help you sell it for a competitive price.
Read Also:
How to Get Low-Cost Life Insurance for Seniors
Some Kinds of Death are Not Covered by Term Life Insurance
How Private Hire Insurance Takes You Out from Problems?
 There’s one more aspect we’d like to discover this time.