Published on: 21 January 2021
Last Updated on: 24 December 2024
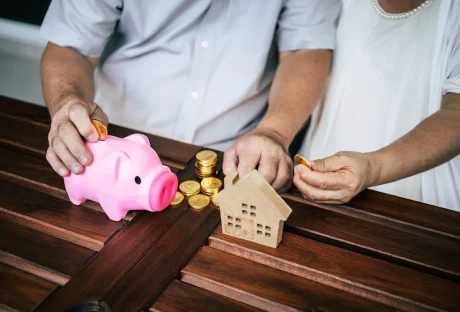
Although it seems like equity release plans have been around forever, this sector of finance has only been regulated since 2004. However, this has not dented their popularity among over 55s wishing to free up a sum of money rather than leaving it tied up in their property.
Many have used the money to fund home DIY projects, help a child onto the housing ladder, or simply for a blowout holiday or new car. Increasingly though many are seeing equity release as a good way to pay for care in their own home in old age. Equity is the value of your home minus any loans or mortgages secured against it which haven’t been fully paid off.
If you’re wondering whether this would be right for you read our advice on the advantages and pitfalls of equity release and how the equity in your home could pay for a comfortable old age.
What is Equity Release and How Does it Work?
This is a method for releasing some of the untapped wealth tied up in your home. Being able to unlock the value of your home and turn this into cash is a way to remain in a much-loved family home. There are two main types of equity release – a lifetime mortgage or a home reversion plan, which is the sale of part or all of the property.
A lifetime mortgage is a loan against the value of your home which is not repaid until either the homeowner dies or goes into long-term care, or the property is sold. If you decide to go down this route you must choose carefully between the two types of lifetime mortgage which are:
The interest roll-up mortgage, which is the most popular option. With this, you receive either a lump sum or regular amounts, and interest is added to the loan at a fixed or capped rate.
An interest-paying mortgage is similar to a standard mortgage in that you pay monthly or ad-hoc payments, and some plans allow you to pay off the capital, to reduce the sum owed at the end.
The home reversion plan is only available to those aged at least 65. With this, you can sell all or a percentage of your home to a provider at below the market value and you become a rent-free tenant in your home. You can even sell percentages of the home at off-set intervals.
Another, less well known and potentially more risky option is the sale and rent back scheme where you sell your home, at a discount and become a rent-paying tenant in your home.
Points to Consider
Home care services are increasingly seen as preferable to standard nursing home care for many reasons, not least among them being able to carry on living in your own home being looked after by a trusted live-in carer who becomes your friend.
Lifetime mortgages are considered the most popular option for equity release because it allows you to retain full ownership of your property and some come with an option of paying back some of the loans over time in order to reduce the build-up of interest and retain as much of the value of your property to benefit your estate when you die.
You can only apply for equity release once you are over 55 and the amount you receive is dependent upon the value of your home (minimum value £70,000) as well as your age. Your property must be in the UK.
Benefits of Equity Release
For today’s older homeowners who have seen the value of their homes rise significantly over recent years and with the added benefit of current low-interest rates, equity release gives you an amount of cash to spend now or to put towards a live-in care plan.
Risks and Pitfalls of Equity Release
The biggest problem with equity release is that you do not receive the full market value for your home, indeed the amount you can access would be much less than you would get by selling your home on the open market in the traditional way. Another disadvantage is that any inheritance your beneficiaries expect to receive would be reduced.
The upfront costs and fees involved in setting up an equity release plan could be as much as £3000.
If you opt for a lifetime mortgage there is a real risk that when the time comes for your home to be sold the amount owed may be more than you borrowed because of the compound interest charged on the mortgage, unless you can pay off some of the debt as you go along. So, if you want to leave a decent inheritance for your family you need to act with caution.
Be aware that if you have a substantial amount of cash in the bank this could affect any means-tested benefits you may be entitled to. The upper threshold is currently £16,000 so above this you are ineligible for means-tested benefits. Your tax situation could be impacted.
If you choose to pay off the whole of the lifetime mortgage early you could incur penalties.
Risks of Home Reversion Scheme
You may only receive between 30-60% of the market value of your home and there may be a clause in your contract which forbids you from moving home. Distressingly, once you die the property usually has to be vacated within one month which causes unnecessary upset to the family at a distressing time.
Protections from the Equity Release Council
You should look for an equity release provider who is a member of the Equity Release Council to ensure that any lifetime mortgage you take out will never exceed the total value of your property. You are also assured that:
You can remain in your home until the end of the mortgage term
You are provided with an independent solicitor who explains everything clearly to you
Interest rates must be fixed or capped and the product must have a ‘no negative equity guarantee'.
Always get the best independent adviser who is regulated by the FCA and discuss things with your family before signing on the dotted line.
Read Also:
Content Rally wrapped around an online publication where you can publish your own intellectuals. It is a publishing platform designed to make great stories by content creators. This is your era, your place to be online. So come forward share your views, thoughts and ideas via Content Rally.
Your financial plan should reflect who you are and what matters most to you. By aligning your money management with your core values, you create a more meaningful and fulfilling financial life.
Here's how to make your financial plan match your personal principles:
Identify Your Core Values
As you consider help with financial planning, start by clarifying what's truly important to you. Reflect on what brings you joy and fulfillment.
Consider the causes you care about deeply and how you want to spend your time and energy. Think about the kind of legacy you want to leave.
List your top 5-7 core values. These might include family, health, creativity, learning, adventure, or community. Be specific about what each value means to you.
Assess Your Current Finances
Take stock of your financial situation. Review your income sources, expenses, spending patterns, assets, and debts.
Look at your insurance coverage, investments, and retirement accounts. Identify areas where your money use aligns with or contradicts your values. Look for opportunities to better align your finances with your principles.
Set Value-Driven Financial Goals
Create financial goals that support your core values. If family is a top value, you might aim to build an emergency fund to protect loved ones.
For those who prioritize learning, budgeting for courses or travel that expand your mind could be key. Make your goals specific, measurable, and time-bound. Prioritize them based on your values.
Create A Values-Based Budget
Design a spending plan that reflects your priorities. Allocate more money to areas that align with your values. Cut back on expenses that don't serve your principles.
Leave room for both necessary costs and value-driven choices. This approach ensures your day-to-day financial decisions support what matters most to you.
Invest According To Your Beliefs
Choose investments that match your ethics and goals. This might include socially responsible mutual funds, environmental, social, and governance (ESG) stocks, or community investment options.
Research options thoroughly. Ensure your investment strategy still provides proper diversification and returns.
Plan For Meaningful Experiences
Budget for activities and purchases that truly matter to you. This could include family vacations, skill-building workshops, or tools for a fulfilling hobby.
Prioritize experiences over material goods when they align with your values. This approach often leads to greater long-term satisfaction.
Build A Value-Focused Career
Seek work that resonates with your beliefs and passions. This might mean changing to a more fulfilling job or starting a values-driven side business.
Consider negotiating for a better work-life balance or pursuing additional education for career growth. A career aligned with your values can boost both financial and personal satisfaction.
Give Back Meaningfully
Incorporate charitable giving into your financial plan. Choose causes that deeply matter to you. This could involve regular donations to favorite nonprofits or volunteering your time and skills.
Consider setting up a donor-advised fund or planning for charitable bequests in your estate.
Tips For Successful Financial Planning
Here is how you can begin being a little more responsible with your financial plans.
1. Start Early To Give Yourself More Time
Ever heard the expression, "The best time to plant a tree was 20 years ago, but the second-best time is now"? The same goes for financial planning. The earlier you start, the more your money can grow and compound.
So why wait? Even if you're starting small, it's never too early or too late to set aside some of your income for the future.
Just think, where do you want to be financially in 5 years? How about in 10 years or even 20 years? When you start early, you give yourself some powerful time that can be your best friend when it comes to multiplying your money quickly.
2. Be Realistic
It’s great to have financial goals for yourself, but be sure they are also attainable. If you’re constantly chasing a goal that is impossible to meet, you’ll do nothing more than frustrate yourself in the end.
For instance, if you want to save $50,000 this year on a salary of $40,000 per year and not change your current lifestyle at all, that isn’t going to happen. Instead, set realistic steps for reaching your ultimate goal and celebrate when you hit each one along the way.
3. Seek Professional Advice
Feeling lost? There’s no shame in asking for help. Financial planning can be complicated and confusing, and hiring a professional to assist you is a great way to gain confidence in your plan. Are you investing as much as you could be? Is your tax bill higher than it needs to be?
Can you do more with your resources? A financial planner can address these concerns and many others that might arise, from figuring out how to retire when you want to decide how much life insurance is enough or what steps need to be taken after the death of a loved one.
Having an expert on call is particularly useful when trying to use money as a tool to get the most out of life.
4. Automate Good Habits
Imagine waking up to find your savings account has grown overnight. You haven’t had to do anything. That’s the magic of automation.
By setting up automatic transfers from checking to savings or direct contributions to your retirement or investment accounts, you’ll be building good financial habits without even thinking about it.
And if all your saving and investing goals are on auto-pilot, you won’t need any willpower at all because a single decision will take care of it for you. This is one of the most effective ways I know of to maintain discipline.
5. Educate Yourself
Your best defense to making well-informed decisions is to educate yourself. Are you staying current with financial trends and opportunities that may affect you?
The more knowledge you possess, the better prepared you will be when it comes to taking action with your finances.
It could be learning about socially responsible investments that match your values or how compound interest actually works. Knowledge enables better decision-making on your part and helps alleviate any concerns or fears you may have.
Read articles, attend webinars, or listen to podcasts just like these so that you can continually tweak and improve upon what’s already working.
By aligning your financial plan with your core values, you create a more purposeful and satisfying relationship with money.
This approach leads to better financial decisions and a deeper sense of fulfillment in your financial life. Remember to stay flexible and adjust your plan as life changes occur.
Read Also:
Simplifying Finance: The Role Of UX Design In Financial Services
Alternative Business Financing – What Is It And How Do You Do It?
Embedded Finance In Online Businesses: The Role Of Account Top-Ups And Currency Exchange
There are many ways to earn extra money.
It could be from being a notary or even from other types of businesses. You can even do something as simple as officiating weddings. This article will tell you all about these different opportunities.
Here Are Five Prime Ways To Earn Extra Money:
1. Signing Agents
Notary Signing Agents help facilitate signings of real estate and loan closings. They are independent contractors. Their fees range from $75 to $200 per loan closing.
If you are considering starting your own notary business, you need to determine the best way to make money. Most states have rules on notary fees, so it's important to know what the going rates are in your area.
You might be interested to know that notaries can also make more money by specializing in different services. Some of these include providing courier services and performing field inspections.
Notary jobs are an easy way to make money in your spare time. You can work in your own home or even travel to clients' offices. Whether you work on a regular basis or just for one client at a time, you can expect to make a decent salary.
Many individuals and businesses benefit from having a commissioned notary on their payroll. The average notary earns $16,000 to $90,000 a year. However, the opportunity to start your own notary business can be overwhelming.
Start your business by networking. Joining a local chamber of commerce is a good place to start. This will give you credibility. Be sure to attend ribbon-cutting ceremonies and trade events.
It's also a great idea to take a notary training course. Whether you want to get certified to perform online notarizations or I-9 forms, you can find courses that will make you a competent signing agent.
Starting your own notary business can be a lot of fun and exciting. You can make a lot of money and gain valuable real-life experience. Plus, a successful business is better than any extra job you can find.
2. Officiating Weddings
Becoming a wedding officiant is an excellent side business to earn some extra money. Although weddings are generally confined to weekends, you can find work during the week.
If you live in a popular area, you can be on the lookout for local couples and use word of mouth to promote your services. It's also a good idea to build up a website for your business.
You'll want to research local laws to ensure your business is legal. For instance, some states require you to register with your county government and have a license to perform marriage ceremonies. The cost of this will vary depending on your geographic location and the number of guests at the ceremony.
Your state will also require you to obtain a license to notarize. Some states do not specify the fee, while others require a minimum amount. In some cases, you may be required to pay for travel time.
Becoming an officiant is usually a straightforward process, but you should be sure to check with your county clerk's office. Otherwise, you may be subject to hefty fines.
You may want to consider attending ribbon cutting and other events where you can showcase your work. This will increase your credibility and help you get more business.
A great way to market your wedding officiant service is to create a website. While it doesn't need to be a complex site, you should include your photo and videos of you performing a wedding. Consider joining a local chamber of commerce, as well.
Another great idea is to attend wedding fairs. These events can be a good place to advertise your business and have the opportunity to meet and greet many brides and grooms.
3. Mobile Service
If you want to make money on the road, a Notary business can be a great option. However, starting a mobile notary business can be a daunting task. You will need to consider many factors, such as vehicle maintenance, business expenses, insurance, and tax reporting.
Mobile Notaries can work part or full-time. Some can earn up to $900 a month while others are making over $12,000 per month. Depending on your location and the type of clients you work with, your income can vary.
Aside from working as a notary, you may also have the opportunity to perform other non-notary duties such as fingerprinting, courier services, field inspections, or escrow services. Be sure to follow all state laws regarding the use of a mobile notary service.
You will need to apply for a license and register your business. The business may also require an employer identification number (EIN).
Creating a personal website can be a great way to market your Notary business. You can also use social media to promote your service.
Another great idea is to attend networking meetings and ribbon-cutting events. Getting involved in the local chamber of commerce adds credibility to your business.
If you're considering a career as a notary, you will need to provide a high level of customer service. Developing a positive attitude is key to your success.
The demand for mobile notaries is projected to rise through 2021. This means that you will have plenty of opportunities to earn extra income. However, you will need to be prepared to take on challenges along the way. This means investing in software solutions such as this App for Notaries in order to simplify and streamline the document signing and notarizing processes and sticking to your business plan.
In fact, one survey found that nearly two-thirds of full-time mobile Notaries earn between $2,000 and $4,000. Nearly thirty percent of part-time Notaries report earning more than $1,000 a month.
4. Chamber Of Commerce
Getting involved in your local Chamber of Commerce is a good way to promote your notary business. You can reach potential clients by advertising on your member's websites or by submitting materials to their newsletter.
Notaries are in demand, so getting involved with your chamber can be a great way to boost your business. The chamber's mission is to promote business and generate more business activity for your community.
Notaries can network with other members of their chamber and other professionals in the community. Using social media to spread the word about your notary services is also a good idea.
Notaries can get involved in leadership positions in their local Chamber of Commerce. In addition, volunteering can help you build your business and keep you connected to the community.
Attending ribbon-cutting events and other business events is a good way to attract new clients. Networking events are also fun ways to meet new people.
Building your referral base is a major factor in your success as a business owner. When you have contacts, you can provide quality service and encourage others to use you. Adding additional services to your notary business is a great way to increase revenue.
Make sure your website and notary business are professional. A good website will provide an overview of your company's history and services.
Be sure to take advantage of all available networking opportunities. These can include attending events, joining notary professional organizations, and contacting other businesses. Also, volunteer at local charities and schools. It is important to remember that a good attitude is key to your business' success.
Start by creating a simple website. This can be done for less than $1,000.
5. Insurance
Notary services are a great way to earn some extra money, and they can be very lucrative. The key is to offer a service that people need and make sure that they know about you.
Aside from notary signs and signatures, there are many other ways to generate business. You can advertise your services, volunteer to be part of a local leadership group, and participate in networking events.
While you’re at it, you should also set up a website. This is a great place to list all of your services and a good place to start. If you’re looking to grow your business, you should also look into SEO. With the right strategy, your site can appear closer to the top of search results for relevant terms.
Taking the time to create a business plan will help you to understand the market better. Your plan should include an overview of your business, its target demographics, and how you will reach customers. For this, you can use automated ap processing, where you can enhance your company’s workflow and offer brilliant service and accuracy in managing accounts and payslips.
Read Also:
Need Some Help Saving Money As A Young Professional? Use Mycare To Learn How To Budget!
10 Ways To Earn Money From Your Mobile Device
Craigslist Knoxville – 5 Money Scams To Consider
Planning doesn’t stop once you retire. In fact, you need to increase your efforts when the day arrives to maintain security. Security can look different for each retiree and their investment portfolio, but one commonality that many agree on is ensuring that the assets are diverse.
Gold and other precious metals keep a retirement portfolio diverse, meaning the assets are not all tied up in one class, nor do they all correlate with the market similarly.
A gold firm, check metal-res.com website for details, will set an investor up with physical gold or a gold IRA to meet plan diversity needs.
A financial counselor or advisor can further assist investors by helping strategize for security up to the age when they decide to retire and after.
Let’s examine what that strategy might look like.
What Will A Financial Retirement Plan Including Gold Look Like
The objective when planning for retirement is achieving security. Even after retiring, retirees must continue strategizing to ensure they don’t lose it. When building an investment strategy, a primary method for establishing a secure portfolio is through diversity.
Many investors accomplish this by adding a physical commodity like precious metals or gold, boasting as an excellent long-term investment. That would make it ideal for a retiree.
Adequate planning for an investment portfolio would include reassessing each year until reaching retirement and after since goals and circumstances change.
One consideration is determining an appropriate age to retire. A problem for some is becoming harried about retiring, tending to jump ship a little too soon without considering the consequences.
These retirees are often unprepared, with a few finding themselves heading back to work. The priority after the fact is following the guidance of a professional financial counselor for the best way out of the pitfall they find themself in.
Other investors are relatively on the mark, with planning working in their favor thus far. Still, striving for security means reassessing the strategy and looking further into the future to discern how the goals will need to change as their lifestyle does.
What steps should you follow to ensure optimum security as you head into retirement? Let’s learn.
Reassess your needs and what you hope to achieve
Each year before retiring and continuing after retirement is reached, it’s wise to consult with a financial counselor to look over your finances, see where you currently stand, and what you see as goals moving forward.
A counselor is in a position to offer advice on where to make adjustments to align your strategy with new objectives.
As a retired investor, you’ll be less risk tolerant with your investment choices. The idea at this stage is to keep a steady flow to withdraw from instead of being intent on amassing a fortune in wealth. You will still want to protect your wealth, making a case for keeping that little bit of gold in your holdings.
The precious metal will provide a store of value and balance the holdings, reducing risk even further.
What is your spending plan?
The recommendation with an established spending plan is to take no more than 4% from retirement savings in a given year. That doesn’t mean sticking with that plan will always be possible, particularly if emergencies crop up, medical expenses, and critical household needs.
When working with a financial counselor or advisor or overall planning for retirement, these things need to be accounted for in the spending plan. That means anticipating that this will be an expense, so you’re prepared for emergencies at any moment.
No one can plan when an emergency might occur, but you can ensure that you have money in the event there is one. That’s the urgency with the need to have a spending plan lined out when you retire.
No risk isn’t reasonable either
You’ll be less tolerant of risk when you retire, perhaps a bit more conservative with your investment choices since recovery takes time when the market spirals. Still, you don’t want such a “safe” portfolio that inflation nibbles it away.
For some, retirement can go on for a couple of decades, perhaps more, depending on when you stop working. These savings need to carry you through that timeframe.
The idea is to have a healthy blend of investments that will continue to grow throughout the years. Plus, if you have that sparkle of gold diversifying your assets, the precious metals will help to reduce your risks, protect your wealth, and stabilize your holdings.
It will take careful planning and adequate guidance to discern investments that are neither too great of a risk nor too minimal but instead offer excellent growth potential.
Some ways to improve funds coming into the household include stocks that pay dividends and setting up annuities. These will be the closest thing to a steady, secure flow of income after leaving the workforce. Open for details on how to retire with “millions.”
Final Thought
Securing retirement, determining when to retire, and planning looks different to everyone. A common denominator is protecting the wealth that you do accumulate.
That usually means reducing the risk of loss. Investing in a precious metal like gold can do both these things and more. It’s also a consistent investment, steady and long-term.
When reassessing your plan and goals plus your lifestyle changes each year, the only constant that could remain true at any age is possibly your gold asset.
Read Also:
Smart Ways to Invest in Gold
How To Start Your Investor Journey: 5 Credible Options To Explore
What Investors Should Know about Investment in Gold and Silver Assets
 This is a method for releasing some of the untapped wealth tied up in your home. Being able to unlock the value of your home and turn this into cash is a way to remain in a much-loved family home. There are two main types of equity release – a lifetime mortgage or a home reversion plan, which is the sale of part or all of the property.
A lifetime mortgage is a loan against the value of your home which is not repaid until either the homeowner dies or goes into long-term care, or the property is sold. If you decide to go down this route you must choose carefully between the two types of lifetime mortgage which are:
 For today’s older homeowners who have seen the value of their homes rise significantly over recent years and with the added benefit of current low-interest rates, equity release gives you an amount of cash to spend now or to put towards a live-in care plan.