Published on: 14 February 2024
Last Updated on: 11 February 2026
In the rapidly evolving business environment, automation has emerged as a transformative force, reshaping various operational aspects, including payroll and compliance processes. This technological advancement has significantly impacted how businesses manage their financial obligations and adhere to regulatory standards, much like workforce management systems have revolutionized employee scheduling and task allocation. Automation in payroll and compliance offers many benefits, ranging from enhanced accuracy to improved efficiency. This article dives into the impact of automation on these critical business functions, shedding light on its benefits and the future it heralds for organizations.
Streamlining Payroll Processing
The advent of automation in payroll processing has revolutionized the way businesses approach this critical function. Beyond merely automating calculations, sophisticated software solutions offer integrated time tracking, direct deposit setups, and even mobile access for on-the-go management. This ensures that every aspect of payroll—from initial hours worked to final payment—is handled precisely and efficiently.
Automated systems adeptly manage varying tax rates and legal requirements for businesses operating across different states or countries, ensuring compliance and accuracy regardless of geographic complexities. The result is a streamlined process that saves time and significantly reduces the administrative burden on staff, allowing businesses to allocate resources to areas that drive growth and innovation.
Enhancing Accuracy And Reducing Errors
Automated payroll systems have become invaluable in enhancing the accuracy of financial transactions and reducing errors. By removing manual data entry, the risk of human error significantly decreases, leading to more reliable payroll outcomes. These systems are designed to automatically update in response to changes in tax laws, employee benefits, and other variables, ensuring that every payment is calculated based on the most current information.
Furthermore, they offer detailed records and reports that can be quickly reviewed and audited, providing additional oversight. This meticulous approach to payroll not only safeguards against compliance issues but also builds trust among employees, who can be confident in the accuracy and reliability of their paychecks.
Improving Compliance With Regulatory Changes
The dynamic nature of tax laws and employment regulations makes compliance a moving target for many businesses. Automated payroll systems are equipped to handle these changes seamlessly by incorporating updates directly into their calculations and reporting features. This automation ensures that businesses remain compliant without needing to monitor and adjust to new regulations manually.
It also provides a significant advantage in risk management, as the system can alert businesses to potential compliance issues before they become problematic. By leveraging automation, companies can navigate the complex regulatory compliance landscape more quickly and confidently, minimizing exposure to penalties and legal issues.
Enhancing Employee Self-Service Capabilities
Implementing employee self-service capabilities through automation has transformed the employee experience regarding payroll and benefits management. These platforms empower employees to take charge of their personal information, view detailed pay histories, and access year-end tax documents independently. This level of transparency and control is a convenience for employees and fosters a sense of empowerment and engagement. Additionally, by decentralizing these tasks, HR departments are relieved of routine inquiries, allowing them to concentrate on strategic initiatives that contribute to the company's culture and growth. This shift improves operational efficiency and enhances the overall workplace environment by promoting a culture of transparency and self-sufficiency.
Facilitating Data-Driven Decision Making
In payroll and compliance, automation provides more than just operational efficiencies; it offers strategic insights. The data collected and analyzed by automated systems can inform various business decisions, from budgeting and financial planning to workforce development strategies. This wealth of data enables companies to identify trends, such as overtime usage or departmental labor costs, allowing for more informed decision-making. By knowing the financial implications of these trends, businesses can optimize their operations, forecast future costs more accurately, and strategically plan for growth. This level of analysis was previously unattainable with manual processes, highlighting how automation not only streamlines administrative tasks but also provides a strategic advantage.
Prioritising Cybersecurity In Automated Systems
An additional point to consider in the context of automation in payroll and compliance is the critical importance of prioritizing cybersecurity. As businesses rely increasingly on digital platforms to manage sensitive employee information and financial data, the potential for cyber threats grows. Implementing robust security measures, including encryption, multi-factor authentication, and regular security audits, is essential to protect this data from breaches.
Furthermore, educating employees about cybersecurity best practices can help mitigate risks associated with phishing scams and other digital threats. By prioritizing cybersecurity within automated payroll and compliance systems, businesses can safeguard their data, protect their employees' information, and maintain the integrity of their financial operations in the digital age.
Conclusion
In conclusion, the impact of automation on payroll and compliance is profound, offering businesses the opportunity to streamline processes, enhance accuracy, improve regulatory compliance, empower employees, and make informed decisions. As technology advances,
automation will likely play an increasingly central role in these areas, much like workforce management systems have become integral to managing modern workplaces. The benefits of automation in payroll and compliance are clear, promising a future where businesses can operate more efficiently, accurately, and compliantly, ultimately contributing to their overall success and sustainability.
Abdul Aziz Mondol is a professional blogger who is having a colossal interest in writing blogs and other jones of calligraphies. In terms of his professional commitments, he loves to share content related to business, finance, technology, and the gaming niche.
Small companies are a vital ingredient of the national economy. In the United States alone, there are 31.7 million small businesses. They provide 64% of all new employment produced in the country. More than half of all small firms fail within the first year, and more than 95% fail during the first 5 years.
Furthermore, 66 percent experience financial woes. For 43 percent of small companies, the challenge is paying operating overhead. This happened after work from home became the mainstream, with a majority of Americans working remotely in the year 2020, lowering expenses for businesses to prosper. Additionally, 60 percent of businesses closed as a result of the virus.
Here are 5 major financial risks to avoid while establishing your business:
1. Don’t Go Up-Beat With The Prices
It is very hard for a business to start with a high price for a product or a service and then tone it down due to lack of engagement. Instead, you should be moderate and even low with the prices at the start because it will get you enough traffic.
But don’t rely on those prices for too long because business needs to thrive, start increasing prices gradually. Use customer service and social media to inform the people of the quality you maintain, people always are ready to pay a little extra if they know the quality is maintained.
2. Avoid Taking a Loan if You Don’t Need One
Just because you are starting your business, does not necessarily mean that you have to have a good amount on one hand. This type of thinking can stress you out even before the process starts and can numb the creative juices.
Furthermore, bank loans are always given with interest, and if your business does not keep up, you might end up in a filthy debt. Try to work with the resources you have and once you have established your name then maybe consider taking out a loan to expand.
3. Think About Having Multiple Business Models In One Business:
If you are a product-based business, don’t just rely on that, if you are a service-based corporate, don’t say that the revenue will be generated only from that. Instead, create an online presence and figure out other means of generating revenues as well. Social media campaigns and blogs can help you get ads and thus more revenue from multiple sources.
4. Getting People Employed When You Don’t Have Money
It’s true that you are on the road to progress but test your business out with self-help in the first months, and when the processes of revenue generation are smooth, then look for additional help. It will save you from the unnecessary mental pressure of paying someone when you are struggling with profits.
5. Always Get a Legal Framework In Order
Work hard on your policies related to customers and services. Invest in getting licit legal help and building the right nest for your legal protection. Getting the right insurance is also a part of building your legal frameworks.
Talisman Casualty is a leading provider of general liability insurance for small contractors in Las Vegas, you can consider them for your business legalities. Having professional help will aid you in making the right decisions timely.
Read Also:
Benefits of NBFC Business Loans
What Are the Alternatives for Small Business Startup Loans?
Are you an enthusiastic, driven individual looking to take a new, exciting step towards your financial goals? Then investing in a College Hunks franchise is the perfect business model for you!
These unique, dynamic, and essential establishments provide clients of all backgrounds with assistance and support when moving from apartments, offices, or other personal services.
The franchise enterprises will give investors an established brand name and reputation to make it in this competitive landscape.
You’ll also be able to receive all the marketing and advertising resources and campaigns needed to grow your business and stand out above the competition in the field. These franchisors will also provide exceptional guidance and tools to grow your business.
This blog article will explore some advantages of investing in a moving franchise business. Let’s get right into it!
New To The Field? Don’t Sweat It!
Kickstarting a business from scratch can be extremely daunting and overwhelming, especially for someone new to a specific field or if you’re a first-time owner in this competitive, unpredictable environment.
This is why so many companies close down two years after opening their doors and entering this unique, exciting industry.
Luckily, when you decide to invest in a franchise business, you’ll gain all the training and educational resources to make it in this competitive industry.
The franchisor will provide your staff members with the best processes for dealing with complex client situations and scenarios. They’ll also be taught how to move items and personal possessions effectively from one place to the next.
As an owner, you’ll gain the strategies needed to lead your business to the highest level and assist you in finding the perfect business ideas to implement to run your enterprise and take it to the next level.
Assistance In Marketing Your Business
Marketing and advertising are two of the most important aspects of a thriving establishment. This is where you’ll be able to communicate with your clients and find the perfect way to speak to your audience.
This is where your consumers will be informed of the various specials, promotions, and changes in your offering. You’ll also be able to receive top-notch expertise to help you gain valuable insights about your business and your employees.
You’ll get the best digital marketing strategy, SEO practices, and social media campaigns that can be used to build your following and take your audience members on a new and exciting journey.
You must remember that social media is one of the most powerful tools you can use to connect with your clients. Facebook, Instagram, and Tiko-Tok are the perfect platforms to grow and thrive in this industry.
With the proper strategy, you’ll grow your following and gain rewards in this sector.
It’s All About The Power That The Brand Carries
Another benefit of investing in a franchise company is that you’ll gain the benefits and advantages that come along with the brand name. It’s important to remember that customers will only use specific businesses they know and respect.
This means that the market has already built a feeling of trust and loyalty towards the brand, knowing they’ll be able to find the help and assistance they’re looking for from the company.
When you own a franchise company, you’re gaining an established brand name along with a loyal group of supporters; this will help you in the long run and assist you in standing out among the various competitors in the field.
By investing in a franchise business, you’re given the power of the brand along with all the fantastic opportunities for growth and success.
Final Thoughts
In conclusion, investing in a moving franchise will bring many benefits and opportunities for you to make lucrative business decisions and grow your following in the field.
You’ll be able to get the perfect marketing and advertising strategies, gain all the training and education you’ll need to thrive, and gain a brand name that has a solid reputation in the sector.
Remember to do your due diligence and research the available options. These resources will be able to provide you with information on moving company start-up costs, what’s needed, and how to go about opening your doors to the public.
Through hard work, dedication, and the willingness to push through difficult situations, you’ll gain success in this competitive world in no time at all!
Read Also:
Franchise Digital Marketing: 4 Effective Techniques
Reasons Why Some People are Sceptical of Franchises
Embedded Finance In Online Businesses: The Role Of Account Top-Ups And Currency Exchange
The aftermath of the COVID-19 Pandemic saw a string of businesses file for bankruptcy. The United States saw many B2B businesses including, FTK Worldwide (Jewellers), Contact Transport (Logistics and Supply), and others opt for the bankruptcy route.
Legal experts are of the opinion that no two bankruptcy cases are the same. They differ in terms of their exposure, risks, legalities, and the court judgment. Even if two companies file for bankruptcy under Chapter 7, their judgments and orders can be different.
In this article, we speak to a leading bankruptcy Birmingham law firm that specializes in these issues. we ask them about some important things businesses and their owners need to keep in mind before filing for bankruptcy.
List of Important Things you need to know before Filing for Bankruptcy
1. Chapters 7 and Chapter 13 are Important for Individuals and Businesses
Legal experts suggest that solopreneur ventures and sole proprietorships that are individual-centric should go for filing bankruptcy under Chapter 7. This puts a stay to debt and credit obligations and allows individuals to even retain control over their property.
Businesses that are well-established should opt for Chapter 11. This helps in keeping the business entity alive and allows for a payment restructuring plan that works to ensure complete repayment over a period of three to five years.
2. Hiring Legal Help is of High Importance
It is important to understand that individuals or businesses looking to file for bankruptcy should always avail of expert legal help. If you are trying to use Google to do all the paperwork, you might get into serious trouble in the near future.
Bankruptcy laws are incredibly complex and technical. In particular, Chapter 7 allows liquidation of debt to take care of financial obligations and absolve the individual from repayment. All collection attempts must stop. Subsequently, a bankruptcy trustee collects non-exempt valuable assets and sells them to pay off debt. The law discharges eligible debts, such as credit card loans, medical bills, and old utility bills. So, you need an experienced bankruptcy attorney to help you fend off the debtors, and work with the courts and the banking institutions. At the end of the day, you do not want criminal proceedings to be initiated by any of the parties.
You can hire an expert in your area, such as a Florida Chapter 7 bankruptcy lawyer. A bankruptcy lawyer’s job is to help you overcome debt, so they’ll guide you through the process by offering advice or assisting you in filing for bankruptcy protection.
3. Bankruptcy does not mean All Debts go away
If you were under the impression that bankruptcy is going to help you walk away scot-free think again. Legally, the following are some areas where bankruptcy will not be able to help you-
Alimony Payments
Student Loans
Taxes on Luxury Items
Taxes
Child Support Payments
All the above-mentioned areas and payments are not something that the court can give you relief from. If you miss your payments or taxes, new legal cases can be brought up against you in a court of law. The punishment and legal repercussions for the same will be different.
For this reason, it’s a must to talk to an experienced attorney and a personal financial advisor who can help you determine other options for addressing these problems. Social workers and community leaders can also help. The government and private sectors offer programs for citizens needing financial and social support services. They’ll help you get through difficult times, so don’t hesitate to consult them.
4. Your Credit Score will get Affected Post-Bankruptcy
According to leading legal experts, ten years is the period where your credit score will carry the blemish of your bankruptcy declaration. If you are looking to get loans or credit during the period, the same might get very difficult. You need to be prepared to address the credit score.
Some lending companies may offer you a personal loan. But the interest rates are high. You can take the risk to recover gradually from poor credit standing. However, you’ll have to make sure that you pay your loan on time.
Fortunately, there are some professional services that have come up in recent years that can help you improve your credit score within a short period of time. If you want to get back in the game, you can always avail of such services.
5. Bankruptcy can help you give Yourself a Fresh Start in Life and Business-
It can be stated that most businesses that suffered because of the pandemic did so for no fault of their own. In such instances, legal experts suggest that bankruptcy can be a sound tactical and strategic decision that can be taken by businesses and individuals.
Banks, lending institutions, and even the judges that will be hearing the case are already aware of the drastic and negative economic fallouts of the pandemic. In fact, there have been cases, where the banks have discussed with lenders and worked out a positive restructuring plan to help individuals and businesses affected by the pandemic.
The Bottom Line
Filing for bankruptcy can probably the single hardest decision you would have to take in your entire life. However, rather than make the decision an emotional one, it is best to exercise reason and proper judgment and take help from an experienced legal attorney to find your way.
Read Also:
Debunking 7 Notorious Bankruptcy Myths
What are the types of debt that can be discharged in bankruptcy?




 The advent of automation in payroll processing has revolutionized the way businesses approach this critical function. Beyond merely automating calculations, sophisticated software solutions offer integrated time tracking, direct deposit setups, and even mobile access for on-the-go management. This ensures that every aspect of payroll—from initial hours worked to final payment—is handled precisely and efficiently.
Automated systems adeptly manage varying tax rates and legal requirements for businesses operating across different states or countries, ensuring compliance and accuracy regardless of geographic complexities. The result is a streamlined process that saves time and significantly reduces the administrative burden on staff, allowing businesses to allocate resources to areas that drive growth and innovation.
 The dynamic nature of tax laws and employment regulations makes compliance a moving target for many businesses. Automated payroll systems are equipped to handle these changes seamlessly by incorporating updates directly into their calculations and reporting features. This automation ensures that businesses remain compliant without needing to monitor and adjust to new regulations manually.
It also provides a significant advantage in risk management, as the system can alert businesses to potential compliance issues before they become problematic. By leveraging automation, companies can navigate the complex regulatory compliance landscape more quickly and confidently, minimizing exposure to penalties and legal issues.
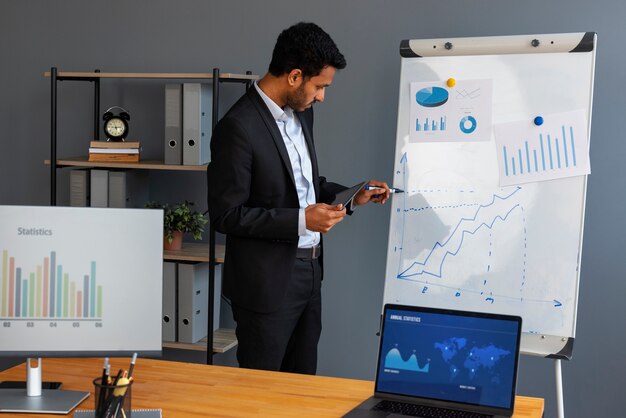 In payroll and compliance, automation provides more than just operational efficiencies; it offers strategic insights. The data collected and analyzed by automated systems can inform various business decisions, from budgeting and financial planning to workforce development strategies. This wealth of data enables companies to identify trends, such as overtime usage or departmental labor costs, allowing for more informed decision-making. By knowing the financial implications of these trends, businesses can optimize their operations, forecast future costs more accurately, and strategically plan for growth. This level of analysis was previously unattainable with manual processes, highlighting how automation not only streamlines administrative tasks but also provides a strategic advantage.