Finding the Perfect Fit: A Landlord’s Guide to Selecting Suitable Tenant

by

09 October 2024

Real Estate

tenants

Even if your rental property isn’t the lifeblood of your income, it’s likely a big part of it. With that in mind, you need tenants who will take care of it, pay their rent on time, and report maintenance needs in a timely manner. But how can you be considerably certain that they meet these criteria? 

In this article, we will provide a short guide for choosing the best tenants. Whether you’re a first-time landlord and just purchased your first apartment complex or you’ve been at this for a while, there are likely some aspects you haven’t thought of. 

But first, Whats a tenant? 
Whats a tenant

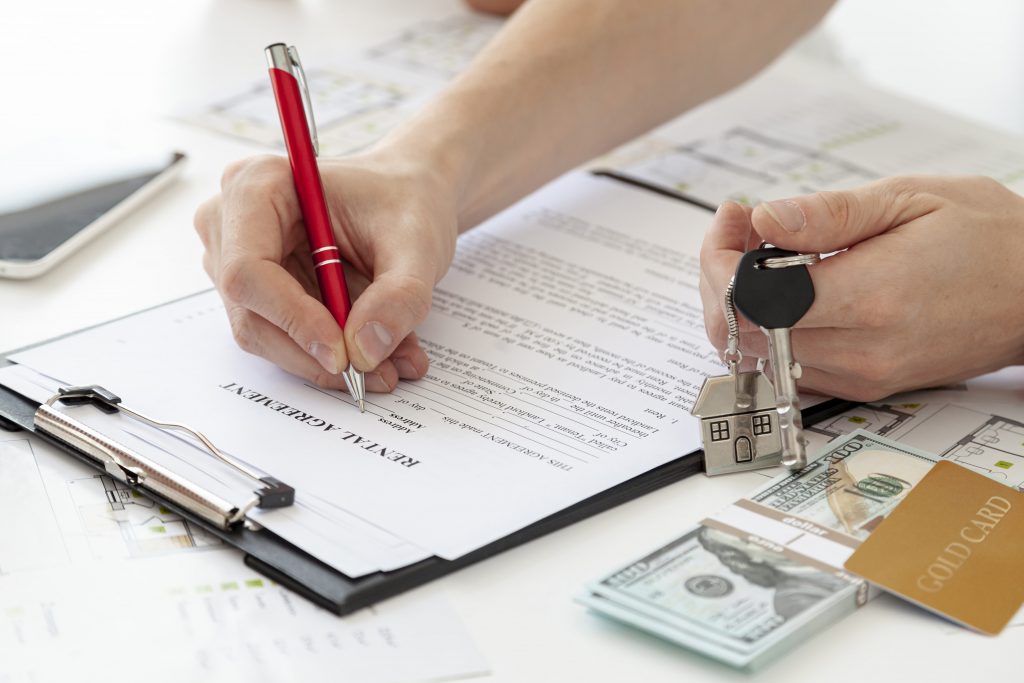
A tenant is a person or an entity who temporarily inhabits another person’s (known as the landlord) property in exchange for an agreed-upon sum of money (rent). There are different types of tenants, such as: 

  • Residential Tenants: Individuals or families renting a home or apartment for living purposes.
  • Commercial Tenants: Businesses that lease office space, retail stores, or other commercial properties.
  • Industrial Tenants: Companies that rent warehouses, factories, or other industrial spaces.

Here are some other key points you should know about tenants. 

Rental Agreement

Tenants typically enter into a rental agreement or lease with the landlord. The terms of use of the tenancy, including the duration of stay or possession, rent amount, and main responsibilities of both parties, are mentioned in this piece of document.

Security Deposit

Tenants often pay a security deposit at the start of the tenancy. The landlord keeps this deposit and uses it to pay for any damages to the rental or unpaid rent when the tenant moves out.

Lease Duration

Tenancies can be short-term (month-to-month) or long-term (typically one year or more). The lease duration is specified in the rental agreement.

Renewal and Termination

At the end of the lease term, the tenant and landlord can agree to renew the lease, or the tenant can choose to move out. Proper notice, as specified in the lease, is usually required for termination.

Eviction

If a tenant fails to comply with the lease terms, such as not paying rent or damaging the property, the landlord may initiate eviction proceedings. However, this process must follow legal procedures to protect the tenant’s rights.

How To Choose A Tenant For Your Rental?

Now that you know who is a tenant, let us take a look at some of some of the aspects you need to keep in mind while choosing a suitable tenant for your rental:

A Major Rule

Per The Fair Housing Act, you have to remember that when it comes to purchasing, selling, renting, or financing a home, it’s illegal to discriminate based on:

  • Nationality
  • Race
  • Skin color
  • Sex
  • Religion

However, you’re not prohibited from basing your decision on the results of a criminal background check.

The Listing

The first thing to remember is that a great rental listing will generally pique the interest of higher-quality applicants and garner more interest overall. To make a quality listing, everyone knows you must have a title that includes the price and the number of bedrooms/bathrooms. But you need to make it stand out with something a little more catchy by highlighting a great feature of the property. Try something along the lines of:

3 bedroom/1.5 bath home with a large backyard with brand new sod, close to schools and parks

In your description, you should use positive descriptors (spacious, cozy, beautiful) to highlight the best features (en suites, fireplace, swimming pool), give details about the area (near downtown, amenities), details about the rental (pets are/aren’t allowed, deposit required, no-smoking) and how potential renters should get in touch with you.

Criteria

If you want to lessen the chances of serving an eviction notice for non-payment, property damage, or other major issues, you need to set the right criteria from the start. Two of the strongest aspects you should consider are credit score and rental history.

While you don’t want to come across as a dreadful landlord, being strict and applying your criteria fairly will help ensure that your new tenant meets the standard you desire. A good place to start is somewhere along the lines of requiring at least a 650 credit score, not having any prior evictions, bankruptcies, or a felony record, and making at least 3x the rent.

Whether you have listed your rental on Zillow, Craigslist, or other listing services, you not only need to be strict in your criteria, but you also need to prescreen them before you even set a face-to-face interview date. You should also prepare pre-screening questionnaires to efficiently determine which leads are worthwhile and which should be put in the rejected folder. However, when making your criteria list, be sure to keep the Fair Housing Act and local tenant rights laws in mind.

Final Checks

Of course, the next logical step is the interviews of potential renters, but that doesn’t mean you will make the first applicant you interview sign a lease on the spot. Take the time to check references from previous landlords, as they can often give you insight that your tenant screening report couldn’t give you. For example, they may have had a lot of neighbor complaints, or they were constantly complaining about minor issues. 

Another thing you should definitely do is a quick Google search of their name. Sometimes, you can find out more this way than with a tenant report. For example, on their application, they claim they’ve worked for sixteen years as an electrician, but the career history on their LinkedIn profile doesn’t match.

Don’t be afraid to do a little sleuthing!

Best Practices To Follow While Interviewing Potential Renters

Conducting face-to-face and thorough interviews and checking references are crucial steps and will help you choose the best tenants for your rental. Here are some tips you can follow to ensure that the interview process goes smoothly. 

  • Verify Identity: Ask for a government-issued ID to confirm the applicant’s identity. This helps prevent fraud and ensures you are dealing with the correct person.
  • Discuss Financial Stability: Inquire about the applicant’s income, employment status, and any other sources of income. A general rule is that the rent should not exceed 30% of their monthly income.
  • Understand Rental History: Ask about their previous rental experiences, including how long they stayed at each place and their reasons for leaving. This can provide insights into their reliability and stability as a tenant.
  • Lifestyle and Habits: Discuss their lifestyle to ensure it aligns with your property’s rules. For example, ask about pets, smoking habits, and how they maintain their living space.

In closing, to find suitable tenants, you should have strict eligibility criteria that also meet the standard of The Fair Housing Act. After shortlisting a few possible tenants, conduct a thorough background check along with a bit of investigative work to choose the best tenant for your rental.

Read More...
Content Rally wrapped around an online publication where you can publish your own intellectuals. It is a publishing platform designed to make great stories by content creators. This is your era, your place to be online. So come forward share your views, thoughts and ideas via Content Rally.

View all posts

Leave a Reply

Your email address will not be published. Required fields are marked *

Related

Vermont Mortgage Loan

Things to Know Before Applying for a Vermont Mortgage Loan

First-time homeowners may be intimidated by the process of purchasing a home. It's not always straightforward to keep track of the stages, the individuals involved, and the resources required to become a homeowner. It's a good idea to acquaint yourself with the method before plunging in headlong. Preparing for a Lender and Selecting a Vermont Mortgage Loan As soon as you're ready to buy a home, it's critical to have some basic knowledge to make the process go smoothly. Find a mortgage lender first. Mortgage lenders provide loans. As a mortgage shopper, you have many options. You can go local or online. You can also choose the type of loan you get. Finding the right lender can be difficult if you've never bought a home before. Before looking for a mortgage lender, you should know what type of loan you want. First, decide whether you want an adjustable or fixed-rate mortgage. It would help if you also considered the loan's duration. The term of the loan determines the interest rate. Pay off the loan as quickly as you can. If you know how long you want to pay back your loan, you can find a lender who offers it. Once you know what you want, you can start searching. Pick a Mortgage Option There are generally three sorts of loans available: i. Private vs. Government Loans The great majority of mortgages in the United States are originated by savings organizations, banks, and mortgage lenders. If you make a down payment of less than 20% on the property, the lender is likely to require you to buy mortgage insurance (PMI). This insurance may be paid in full at closing or rolled into the loan. VA loans do not require mortgage insurance, but they are only available to qualified veterans. Mortgage insurance protects the lender to some extent when a borrower defaults on a loan. FHA and VA loans are distinct from conventional loans in that the government does not lend the money directly but rather guarantees (or insures) repayment to the lender in the case of default. Because government loans require a lower down payment and usually have a lower interest rate or points, they provide a variety of significant advantages over conventional loans. Unlike private loans, which are not subject to these limitations, government loans take longer to process, have higher closing costs, and have a lower maximum loan amount. Many government loans also require that the property being bought be in reasonable condition, which precludes the purchase of a "fixer-upper." ii. New vs. Assumable Loans Certain types of loans, such as FHA and VA loans, and some adjustable-rate loans, may be eligible for rollover. This means that a new owner may assume an existing debt under the same terms as the previous one. In some instances, obtaining a loan may save both money and time. Typically, the buyer pays an assumption fee at closing to cover the lender's costs for completing the deal. iii. Variable vs. Fixed Rate Loans Fixed-rate loans come with a fixed interest that lasts for the loan duration. In other words, your monthly payment will remain constant unless escrowed taxes and insurance premiums vary. Interest rates and monthly payments on adjustable-rate mortgages (ARMs) can fluctuate over time. These mortgages typically offer lower interest rates, lower monthly payments, and fewer fees and points than fixed-rate mortgages, making them an attractive option for first-time homebuyers, younger couples whose incomes are expected to grow in the future, and individuals who may lack the necessary funds for a down payment and closing costs. Determine the Lender Type Having a basic understanding of the different types of lenders is helpful when comparing financiers. First, there are mortgage lenders employed by banks or other organizations responsible for setting the loan terms and the repayment schedule and costs. "Direct lenders" are also known as "retail lenders." Instead of going through an intermediary, they directly sell their mortgage products to customers. Loans made by correspondent lenders are originated and funded by them, but they are sold to larger lending institutions as soon as they are completed. As an intermediary between lenders and customers, mortgage brokers act on behalf of their clients. Commissions are not owned by either the borrower or the lender. Loan brokers can tailor lenders and loan programs to your specific needs. You might be able to negotiate lower interest rates and terms with several different lenders with their help. Documents Required for a Vermont Mortgage Loan Keeping track of one's finances is advantageous. To expedite and streamline the pre-approval process, ensure that you have all of your financial information organized. If your documentation is well-organized and readily available to lenders, you'll be able to get a loan more quickly. These are some of the most common documents that most financiers will need: W-2 forms for the previous two (2) tax years A copy of the agreement or contract for the purchase and sale is required. (If you already have a deal in place with the vendors, Pay stubs for the last thirty (30) days. If you only have one, that will suffice for the time being. The most recent 401(k), IRA, or mutual fund transaction is summarized. If you cannot locate these, provide the lender with an estimate of your non-liquid assets, and they will work with that. Photo identification Two of the most recent monthly bank statements in their entirety Provide the last two years of corporate returns, including K1s, if you are self-employed through a corporation. For self-employed borrowers, commission-based salespeople, and landlords, most lenders require federal tax returns for the last two years, including all schedules. The only thing standing between you and your first home might be the Vermont mortgage loan process, which can be overwhelming if you’ve never purchased a house before. It would be best to have reliable and trustworthy guidance to help you navigate the housing market. You want a lending institution, like New England Federal Credit Union, that puts a team to work for you. Be sure you have experienced Vermont mortgage loan experts on your side, from application to closing, for peace of mind and assurance that you’re getting the home you love. Read Also: Things to know before buying a new house Everything You Need To Know About A Post Office And Its Services When Is The HAMP Program Beneficial To You? 10 Ways a Low Credit Score Can Negatively Impact Your Life

READ MOREDetails
Conforming Loan Limits In California

Understanding Conforming Loan Limits In California: Unlocking Home Financing Opportunities

When it comes to purchasing a home, access to affordable financing plays a crucial role in making the dream of homeownership a reality. In California, conforming loan limits serve as a key factor in determining the maximum loan amount that lenders can offer while still qualifying for favorable terms and conditions. This article aims to provide a comprehensive understanding of conforming loan limits in California, exploring their definition, significance, factors influencing their determination, and the impact they have on homebuyers and the real estate market. I. Defining Conforming Loan Limits: In order to understand what these loan limits are all about, there are some factors that you might need to know first. A. Definition: Conforming loan limits refer to the maximum loan amounts established by government-sponsored entities (GSEs) such as Fannie Mae and Freddie Mac. These limits delineate the boundary between conforming loans and jumbo loans, which have higher loan amounts and typically carry different terms and requirements. B. Purpose: Conforming loan limits ensure liquidity in the mortgage market by establishing a standardized framework for mortgage lending. They aim to strike a balance between affordable financing for homebuyers and risk management for lenders. Ii. Determination Of Loan Limits In California: Have you ever wondered how to determine conforming loan limits? If yes, here is a checklist for your assistance: A. Federal Housing Finance Agency (FHFA): The Federal Housing Finance Agency (FHFA) is responsible for setting these loan limits annually based on guidelines established by the Housing and Economic Recovery Act (HERA) of 2008. The FHFA considers various factors, including home price indices, to determine appropriate loan limits for different areas. B. County-Level Variation: Conforming loan limits can vary by county within California. The FHFA assesses each county's median home prices to determine county-specific loan limits, taking into account local housing market dynamics. C. VA Loan Limits: For those who are opting for VA-conforming loans in California, there is good news! These loans are no longer having any county loan limit for the year 2023. In “VA Circular 26-19-30,” the VA declared that Trump, the then president, had signed a pledge that eliminates all county loan limits. Veterans can make maximum use of it. Iii. Significance Of Conforming Loan Limits: Without discovering the importance of conforming to loan limits, you cannot opt for one. Go through the significances below: A. Accessibility To Affordable Financing: Conforming loan limits play a vital role in ensuring that a significant portion of homebuyers can access affordable financing options. By setting loan limits that align with local median home prices, these limits promote homeownership opportunities for a broader range of individuals and families. B. Favorable Terms And Conditions: Loans that fall within such loan limits generally enjoy more favorable terms, interest rates, and down payment requirements compared to jumbo loans. This affordability factor enhances borrowers' purchasing power and reduces barriers to entry into the housing market. C. Mortgage Market Stability: Conforming loan limits contribute to the stability of the mortgage market by facilitating the securitization and sale of mortgage-backed securities to investors. Thus, this process helps lenders manage risk and maintain a steady supply of mortgage funds for borrowers. D. Fewer Hassles Of Form Completion: Conventional conforming loans are usually not backed by any government entity. As a result, there is less red tape by the government to interfere with the approval. You will still be eligible for closing disclosure as well as a loan estimate form that will review your closing prices and fees. The frequency might be at the start and end of the mortgage procedure. Iv. Impact On Homebuyers And The Real Estate Market: Did you know that such loan limits usually have a big impact on the realty market as well as homebuyers? Conforming loan limits might have the following impacts on the purchasing decision of a homebuyer. A. Homebuyer Flexibility: A Conforming loan limit provides homebuyers with a wider range of financing options, enabling them to choose loans that align with their financial capabilities and homeownership goals. Hence, this flexibility promotes market activity and supports a sustainable real estate ecosystem. B. Housing Affordability: Conforming loan limits play a crucial role in preserving housing affordability. By capping loan amounts, they help prevent excessive price inflation and contribute to a more balanced as well as accessible housing market. C. Local Market Dynamics: Loan limits that consider county-specific median home prices reflect the unique dynamics of each local housing market within California. Moreover, this approach ensures that loan limits remain relevant and responsive to the economic realities of specific regions. V. Future Considerations: While opting for loan limits, there are certain considerations that should be made. If you are new to the market, here is what you need to discover:  A. Changing Market Conditions: Conforming loan limits may evolve over time in response to changing economic conditions, shifts in home prices, and housing market trends. Homebuyers, as well as industry professionals, should stay informed about updates to these loan limits to make informed decisions. B. Legislative And Regulatory Changes: Furthermore, policy changes at the federal level may influence conforming loan limits in California. Monitoring legislative and regulatory developments can provide insights into potential modifications to loan limits and their implications for the housing market. C. Possibilities Of Loan Limit Increase: According to HERA or the Housing and Economic Recovery Act, there might be an increase in the conforming loan limits by 2023. This reflects the changes in the percentage of average U.S. residential pricing. The time period is somewhere from 12 months to four quarters, and it will end before the annual adjustment determination. Conclusion: Conforming loan limits serve as a critical framework for home financing in California. Consequently, striking a balance between affordable access to credit for homebuyers and prudent risk management for lenders. By setting maximum loan amounts that reflect local housing market dynamics, such loan limits promote homeownership opportunities, housing affordability, and market stability. As the real estate landscape evolves, understanding and navigating these loan limits is essential for individuals and professionals seeking to participate in California's vibrant housing market. We hope this article made it easier for you to understand the various aspects of a conforming loan limit. Is there anything you would like to share? Let us know in the comment box below. Happy reading! Read Also: Choosing a Mortgage Broker for Your Home Loan Application Get Fast Access to Car Title Loan during Bad Times How Do Construction Loans Work?

READ MOREDetails
Heavy Machinery In The Construction Industry

The Power Of Heavy Machinery In The Construction Industry

Construction is on the rise across the United States. From single-family homes and apartment complexes to commercial projects, reports show that construction companies are going to have their work cut out for them in the years to come. Having the right equipment on hand to complete that work is the key to their success. Heavy machinery holds a great deal of power in the construction industry, making it essential for several reasons.  Effective Project Completion Being able to effectively complete projects is one of the most basic benefits of having a diverse heavy equipment supply at a construction company's disposal. Without the proper equipment for the jobs at hand, construction companies are bound to experience problems and delays. They may spend more time than necessary trying to complete tasks with inadequate equipment, which could impact their clients' timelines as well as their own profits. With the heavy machinery they need, construction crews can complete projects faster and more effectively while remaining on budget. They'll be able to use their resources more efficiently, possibly reducing labor and material costs. Each piece of machinery has the potential to improve a company's performance, productivity, and bottom line.  Cost-Effectiveness Cost-effectiveness is also a key consideration. Trying to complete a project with outdated, broken-down equipment can cause countless problems. Those include costly delays, wasted materials, increased workloads for crew members, and quality issues to name a few. Heavy machinery that's in good condition and suited to the specific requirements of a project greatly reduces those problems and the risks that come with them. It also reduces repair costs to further ramp up cost-effectiveness.  Improved Safety Safety is crucial in the construction industry. Workers are up against numerous hazards on construction sites. Using the wrong types of equipment to complete certain tasks can exacerbate those dangers. Working with equipment that's in poor condition and prone to breakdowns makes matters even worse. Having the right heavy machinery on-site reduces the risks of injuries. Equipment that's in good repair improves worker safety as well.  Versatility Having a variety of equipment on hand gives construction companies more versatility too. It allows them to accept projects with confidence that they'll be able to complete them. They won't have to limit themselves to only the projects they're equipped to handle. It also gives them the power to adapt to challenges and unexpected developments they face on the job. With the right heavy machinery in their arsenal, their projects can go smoothly no matter how many problems arise along the way. Professional Reputation Companies that have a selection of heavy machinery to work with tend to have more positive reputations as well. Those who are ill-equipped to handle certain jobs often end up with numerous complaints against them and low client satisfaction rates. On the other hand, construction companies that have the equipment they need to meet clients' expectations are more likely to develop reputations for excellence. That, in turn, can generate repeat business and draw in a steady stream of new clients.  Equipping Yourself for Success Several types of heavy machinery are available for construction companies to take advantage of. Though not all companies need every piece of equipment on the market, having an extensive selection to work with can be advantageous. It helps construction crews to complete projects more safely and effectively. It also gives them greater versatility and leads to improved cost-effectiveness. All those factors enable them to better meet clients' demands and can help bolster their professional reputations.  Read Also: Construction Safety Systems: Promoting A Safer Industry Is Prefabricated Metal The Future Of Warehouse Construction? 7 Common Construction Project Management Problems

READ MOREDetails